At its core, financial reporting is more than just a routine documentation of income, expenditure, and balance—it is the structured articulation of an organization’s life story. It tells of aspirations met or missed, of resources gathered and deployed, and of obligations honored or deferred. Through standardized statements such as the income statement, balance sheet, and cash flow statement, financial reporting offers a window into the true condition of an enterprise—laying bare its strengths, vulnerabilities, and potential trajectories.
Rooted deeply in Accounting and fortified by critical frameworks like Tax Compliance and Planning, Auditing, and Budgeting and Cost Management, financial reporting brings clarity, structure, and accountability to financial disclosures. These interlocking disciplines serve as checks and balances, ensuring that the story told by the numbers is both accurate and ethically sound. The credibility of these reports becomes the basis for investor confidence, executive strategy, employee engagement, and public trust.
Within the broader domain of Business, Economics and Law, financial reporting is the connective tissue that links intention to outcome, and strategy to results. For decision-makers in Business Administration, it provides a foundation for evidence-based planning across domains such as Finance, Operations Management, and Strategic Management. These functions depend on reliable reports not merely to track past performance but to model future scenarios, allocate resources wisely, and align departmental actions with broader organizational goals.
Even in domains often perceived as less numerically driven, such as Marketing and Business Analytics, financial reporting plays a critical role. Marketing campaigns are evaluated not only on reach or engagement but on return on investment (ROI), and data scientists require access to structured financial records to build accurate models and detect meaningful trends. In International Business, reporting takes on added complexity—adapting to multiple currencies, legal jurisdictions, and cross-border regulatory standards—yet remains indispensable for multinational coherence and accountability.
Beyond guiding internal decisions, financial reporting has profound implications for organizational compliance and legitimacy. It supports planning in Human Resource Management, underpins contractual agreements, and helps maintain alignment with national and international legal structures laid out in Corporate Law. This includes essential aspects of Corporate Governance, Compliance and Regulatory Adherence, and increasingly, ethical reporting obligations around environmental, social, and governance (ESG) metrics. These documents become critical during contract negotiations, mergers and acquisitions (M&A), and the protection of intellectual property.
Its influence does not stop at the organizational level. Financial reporting feeds into macroeconomic analysis and policy analysis, shaping fiscal policy, tax structures, and market regulations. Governments, think tanks, and economists rely on aggregated reports to understand economic trends, identify risks, and guide legislative reform. Thus, financial reporting bridges private enterprise with public policy, making it a cornerstone of both economic growth and institutional accountability.
The advent of data visualization and digital reporting tools has further democratized access to financial insights. When financial data is presented not just in dense spreadsheets but in intuitive dashboards and infographics, it becomes a language that more people can understand—across functions, departments, and levels of expertise. This democratization enhances cross-functional dialogue, encouraging collaboration between finance professionals, operational managers, and strategic planners.
Moreover, financial reporting transcends the boundaries of commerce. In fields like Public Health, transparent reporting ensures accountability for grants, medical program funding, and community service initiatives. In education, students and future professionals are taught to see reporting not only as compliance but as a critical thinking tool—an interface where numbers meet narrative, and strategy meets ethics.
Ultimately, financial reporting is a discipline of honesty. It asks institutions to confront their realities, articulate their journeys, and declare their commitments. When practiced with integrity, it does not just record the past—it equips organizations to shape the future with wisdom and trust. It is, quite literally, the language in which organizations tell the world who they are—and who they intend to become.
This image offers a stylized representation of financial reporting, featuring a central financial dashboard surrounded by pie charts, bar graphs, line charts, numeric indicators, and analytic symbols. A magnifying glass emphasizes the importance of scrutiny, transparency, and accuracy in reporting processes. Accompanying tools like a calculator and clock reinforce the roles of precision and timeliness in compiling financial statements. The layout encapsulates the core of financial reporting—transforming raw data into meaningful insights that inform stakeholders, ensure regulatory compliance, and drive business decisions.
Transparency and Disclosure in Financial Communication Systems
What Is a Financial Report? A Mirror of Organizational Integrity
A financial report is far more than a collection of ledgers and line items—it is a formalized expression of an organization’s financial truth. Through carefully prepared and publicly disclosed documents such as the income statement, balance sheet, and cash flow statement, financial reporting distills the complexity of business operations into structured insight. It offers a coherent view of how money is earned, spent, invested, and retained over a specific period, and provides a snapshot of an organization’s fiscal position at a given moment in time.
These reports do more than summarize performance—they narrate the financial journey of the entity, tracing the pulse of cash through every revenue stream and expense category. Each report is rooted in the principles of Accounting and shaped by frameworks such as Budgeting and Cost Management, Auditing, and Tax Compliance and Planning. Together, these ensure that the numbers presented reflect both operational reality and ethical responsibility.
The process of compiling a financial report is meticulous. Revenues must be recognized accurately, expenses classified properly, and assets valued in accordance with prevailing accounting standards. Yet beyond the numbers, what emerges is a document that invites judgment, builds trust, and provides the foundation for economic dialogue between an organization and the outside world. In this sense, financial reports are not just for accountants—they are public declarations of stewardship, competence, and transparency.
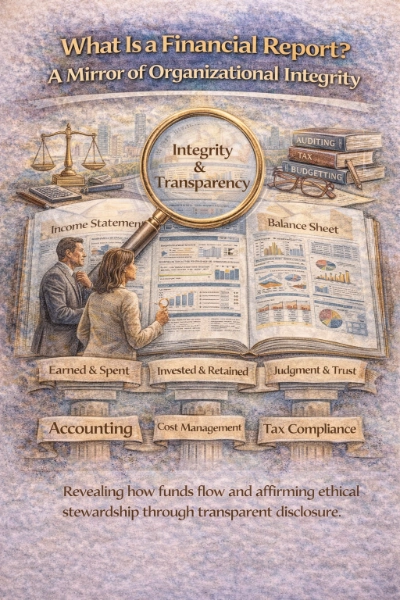
A watercolor-style infographic that frames financial reporting as a public expression of trust and stewardship. The title reads “What Is a Financial Report? A Mirror of Organizational Integrity.” At the center is an open report book with two prominent sections—Income Statement and Balance Sheet—filled with charts and tables. A large magnifying glass overlays the pages with the words “Integrity & Transparency,” symbolizing verification and clarity. Supporting elements include a set of balance scales, a calculator and pen, and stacked reference books labeled Auditing, Tax, and Budgeting, reinforcing the standards and disciplines behind credible reporting. Along the bottom, banner phrases such as “Earned & Spent,” “Invested & Retained,” and “Judgment & Trust” connect financial statements to real-world decisions. The overall layout communicates that financial reports transform complex operations into structured insight while affirming ethical responsibility.
Financial Reporting as a Pillar of Transparency, Accountability, and Strategic Insight
1. Transparency
Transparency is the soul of financial reporting. Stakeholders demand visibility into financial workings. Every disclosed figure, footnote, and ratio must speak with honesty, revealing the ethics and rationale behind resource allocation.
2. Accountability
Financial reporting upholds accountability, transforming internal actions into publicly reviewable outcomes. It assures shareholders, suppliers, employees, and regulators that operations take place under fiscal and moral scrutiny.
3. Decision-Making Support
Serving as a strategic compass across Finance, Operations Management, Strategic Management, and Marketing, financial statements guide investments and market positioning.
In the age of data visualization, this decision-making role is magnified. When financial reporting is paired with accessible visual tools, it becomes understandable to non-experts and empowering for collaborative governance. What was once the language of accountants becomes a shared platform for strategic alignment.
Ultimately, financial reporting is a moral and intellectual discipline. It turns money into meaning, performance into insight, and risk into responsibility. It links the past to the future, the internal to the external, and the numeric to the narrative. It is a language all serious organizations must learn to speak fluently—not merely to comply, but to connect, to clarify, and to lead with integrity.
Essential Parts of Financial Reporting
GAAP and IFRS Standards
Definition: Rules providing frameworks for consistent financial reporting globally, governed by GAAP and International Financial Reporting Standards (IFRS).
- GAAP: Specific rule-based standards common in the U.S.
- IFRS: Principles-based standards used in 140+ countries.
- Application: Ensures regulatory compliance and enables cross-border investment.
External Reporting
Definition: Disclosing standardized financial information to external stakeholders like investors, creditors, and government bodies.
- Key Outputs: Annual reports, earnings reports, regulatory filings (e.g., Form 10-K).
- Application: Attracts capital and confirms creditworthiness for debt financing.
Internal Reporting
Definition: Generating customized financial data for executive leadership to manage operations and strategic resource allocation.
- Key Outputs: Management reports, KPI tracking (ROI, profit margins), budgets.
- Application: Guides internal cost-cutting, process efficiency, and risk planning.
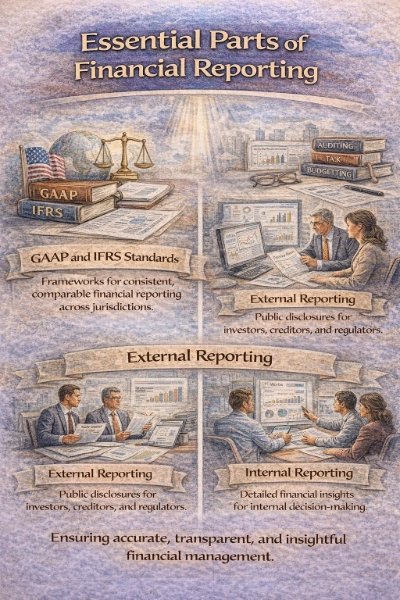
A watercolor-style educational infographic explaining the main components of financial reporting. The title reads “Essential Parts of Financial Reporting.” The top-left section, GAAP and IFRS Standards, shows reference books labeled GAAP and IFRS beside a globe and balance scales, symbolizing global comparability and consistent rules. The upper-right and lower-left sections illustrate External Reporting, with professionals compiling and presenting reports and charts, representing annual reports, earnings updates, and regulatory filings shared with investors, creditors, and regulators. The lower-right section, Internal Reporting, depicts a meeting around screens and dashboards, highlighting management reports, KPIs, budgeting, and forecasting used for operational decisions. A closing line emphasizes the goal: accurate, transparent, and insightful financial management.
Applying Financial Reporting in Corporate and Regulatory Contexts
Publishing Annual Reports for Shareholders
Annual reports offer shareholders a comprehensive overview of financial performance, corporate governance, and long-term trajectory. They build investor trust by highlighting strategic R&D achievements, capital allocations, and program outcomes.
Securing Capital and Lenders
Verified financial statements demonstrate solvency, cash flow strength, and creditworthiness. Startups and established developers present verified balance sheets and income forecasts to negotiate favorable loan terms, Series A funding, or private equity.
Financial Reporting at Work: Practical Examples
Investment Decision Analysis
Scenario & Outcome: Investors analyze an entity’s three core financial statements to assess liquidity and profit margins, enabling data-driven equity acquisition decisions.
Cross-Border Regulatory Compliance
Scenario & Outcome: Multinational firms align local operations with IFRS, preventing regulatory penalties and establishing international market credibility.
Strategic Resource Reallocation
Scenario & Outcome: Retail chains use internal divisional reporting to spot underperforming assets, shifting capital to high-return regional branches.
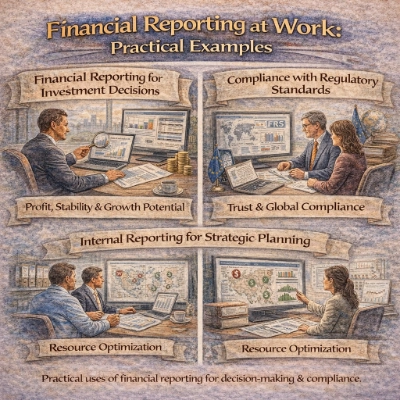
A square watercolor-style infographic illustrating three practical uses of financial reporting. The top-left panel shows an investor examining financial statements on a laptop with charts and a magnifying glass, representing decisions based on profitability, stability, and growth potential. The top-right panel depicts professionals reviewing documents and screens labeled with international standards cues, symbolizing IFRS-aligned compliance and trust across global stakeholders. The bottom section shows managers analyzing internal dashboards and maps to identify underperforming retail locations and redirect resources to stronger sites, highlighting internal reporting for strategic planning and performance improvement. The overall composition uses parchment-style banners and muted blue-gold tones to communicate clarity, credibility, and data-driven decision-making.
Modernizing the Ledger: New Directions in Reporting
- Digital Transformation: Leveraging modern technology like blockchain, AI, and cloud computing to automate ledger entries, enhance verification, and increase audit precision.
- Sustainability Reporting: Integrating ESG metrics directly into corporate reporting to satisfy stakeholder demands regarding climate risk and workforce diversity.
- Real-Time Reporting: Moving away from lagging quarterly reports by deploying live dashboards and automated reporting streams for faster strategic decisions.
- Global Convergence of Standards: Harmonizing U.S. GAAP and IFRS rules to streamline international reporting for global enterprises.
- Data Analytics Integration: Applying predictive modeling to historical financial datasets to isolate primary profit drivers and project market trends.
When Transparency Meets Obstacles: Reporting Difficulties
- Regulatory Compliance: Navigating rapidly evolving, multi-jurisdictional tax laws and accounting guidelines.
- Accuracy and Integrity: Maintaining error-free ledger inputs and preventing corporate fraud across complex operations.
- Data Complexity: Managing, storing, and consolidating massive financial datasets across global subsidiaries.
- Stakeholder Expectations: Balancing detailed regulatory disclosures with clear summaries for general equity investors.
- Sustainability Metrics Integration: Quantifying intangible social and environmental metrics alongside traditional monetary items.
Interactive Tool: Financial Statement & Ratio Analyzer
Input core financial metrics to calculate key reporting statement outputs, profitability ratios, and balance sheet indicators in real time.
Calculated Statements & Financial Ratios
A Vital Skill for Financial and Corporate Professionals
Understanding the Language of Business
Financial reporting provides a structured way for organizations to communicate their financial performance and position. For students preparing for university, learning financial reporting helps build a foundational understanding of how businesses operate, earn revenue, and manage costs. It introduces students to key financial statements such as the income statement, balance sheet, and cash flow statement—tools that are central to business decision-making and university-level accounting or finance studies.
Enhancing Financial Literacy and Confidence
Studying financial reporting improves students’ ability to read and interpret real-world financial data. This builds financial literacy and confidence when encountering balance sheets, annual reports, or financial news. For students entering university programs in business, economics, law, or public administration, this early exposure makes it easier to follow lectures, participate in case studies, and complete assignments that involve financial analysis or corporate evaluation.
Learning to Analyze and Interpret Information
Financial reporting is not just about recording numbers—it is about interpreting what those numbers mean. Students learn how to assess a company’s profitability, liquidity, solvency, and operational efficiency. These analytical skills are highly transferable across academic disciplines and professional fields. By understanding how to extract insights from financial reports, students become more effective problem-solvers and critical thinkers in both academic and real-world settings.
Appreciating Transparency and Ethical Responsibility
Accurate and transparent financial reporting is essential for maintaining investor trust, regulatory compliance, and public accountability. Studying financial reporting introduces students to ethical considerations such as fair presentation, disclosure requirements, and the consequences of misreporting. This emphasis on transparency and integrity reinforces the values that will guide students throughout their university education and future careers.
Preparing for Academic and Professional Advancement
A solid understanding of financial reporting lays the groundwork for advanced study in accounting, finance, auditing, corporate law, and business management. It is also highly relevant for students interested in pursuing professional certifications such as CPA, ACCA, or CFA. For students preparing for university, financial reporting offers a clear and practical entry point into the world of business and finance, equipping them with essential knowledge and skills for long-term success.
Bringing Clarity to the Books: The Enduring Power of Financial Reporting
Financial reporting is not merely a technical procedure—it is a declaration of truth, a disciplined reflection on the economic soul of an organization. To report financially is to bear witness to how an entity has moved through time, how it has used its resources, honored its commitments, and positioned itself for what lies ahead. It is a language of accountability and transparency that transcends spreadsheets and audits, forming the structural core of modern business integrity.
As a foundational pillar of corporate governance, financial reporting supports the architecture of responsible leadership. It provides a factual foundation upon which executives, boards, regulators, and investors build their decisions. In this way, it becomes the bridge between what a business does and what the world sees. Financial reporting does not create reality—but it compels reality to be seen clearly, stripped of illusion, distortion, or selective memory.
At the heart of financial reporting lies a commitment to standardized accounting practices. These global conventions—whether aligned with International Financial Reporting Standards (IFRS) or Generally Accepted Accounting Principles (GAAP)—serve as a common grammar through which the financial narratives of different entities can be compared, interpreted, and trusted. Without this consistency, every report would be a dialect; with it, we gain fluency in understanding value, risk, and progress across industries and borders.
But financial reporting is more than conformity—it is also a dual lens. On one hand, external financial reporting provides shareholders, governments, analysts, and the public with a snapshot of performance, position, and compliance. On the other hand, internal financial reporting—through managerial accounts, forecasts, and cost analysis—offers strategic insight to leadership, enabling informed, agile, and ethical decisions. Together, these modes of reporting empower both accountability and adaptability.
In the age of data visualization and real-time dashboards, reporting is no longer a static retrospective exercise. The field is undergoing a profound transformation. Digital technologies such as AI-powered analytics, cloud-based accounting platforms, blockchain verification, and integrated ERP systems are reinventing what it means to “close the books.” These tools reduce human error, enhance speed, and allow for richer contextual interpretation—helping both CFOs and line managers to see beyond numbers to the operational story they tell.
Simultaneously, the imperative for sustainability reporting is redefining what counts as performance. Environmental, Social, and Governance (ESG) metrics are increasingly being integrated alongside traditional financial indicators. This reflects a shift in stakeholder expectations: profitability alone is no longer sufficient. Investors, consumers, and regulators now want to know whether a company is sustainable, ethical, and socially responsible. In this light, financial reporting becomes a mirror of corporate conscience—capable of revealing not just how a company performs, but how it behaves.
As organizations grow in size and complexity, so too do the expectations placed on their reporting systems. Multinational firms must navigate international business regulations, currency fluctuations, and geopolitical risk. Tech startups may face investor demands for predictive valuation and agile budgeting. Public institutions are scrutinized for fiscal discipline and public service impact. Across all these contexts, financial reporting must maintain both accuracy and relevance—staying true to its historical roots while embracing innovative frameworks for future readiness.
Moreover, financial reporting functions as a tool for fostering organizational growth. By providing a shared understanding of where resources flow, where bottlenecks exist, and where opportunities lie, it becomes a catalyst for internal alignment. Strategic plans, HR budgets, operational initiatives, and marketing investments all draw strength from a clear, common financial language. In this way, reporting is not the end of a process—but the starting point of disciplined action.
The role of auditing further reinforces this dynamic. Independent verification adds a second layer of trust, offering assurance that reported figures are not only accurate, but free from manipulation. This dual mechanism—transparency through reporting, and assurance through auditing—forms the ethical backbone of modern commerce.
Just as importantly, financial reporting nurtures trust. Trust within teams, between departments, and with the outside world. When stakeholders know that they can rely on the information presented, they are more willing to invest, collaborate, and innovate. Trust, however, is fragile. One instance of misreporting or opaque disclosure can unravel years of careful governance. Thus, reporting is both a technical skill and a moral practice. It demands clarity not only in calculation, but in character.
In today’s volatile economy—marked by uncertainty, digital disruption, and growing calls for social responsibility—the role of financial reporting has never been more essential. It does not merely reflect the past; it guides the future. It does not only count money; it cultivates meaning. Through its enduring commitment to truth, transparency, and timeliness, financial reporting remains the compass by which organizations find direction amid complexity.
To bring clarity to the books is not simply to balance ledgers—it is to affirm an institution’s identity, uphold its values, and declare its readiness to grow responsibly in a world that demands both performance and purpose.
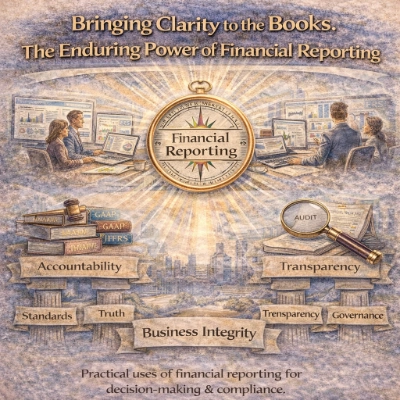
A watercolor-style educational infographic that portrays financial reporting as the guiding center of business integrity. A glowing compass labeled “Financial Reporting” sits at the center, radiating light across scenes of professionals reviewing digital dashboards and reports—symbolizing modern analytics, internal insight, and timely decision support. On one side, stacked reference books labeled GAAP and IFRS emphasize standardized accounting as a shared grammar for comparability and trust. On the other, a magnifying glass over an “Audit” document highlights independent assurance and verification. Classical pillars and banners labeled Accountability, Transparency, Standards, Truth, and Governance frame the message: clear reporting and credible assurance together form a foundation for responsible leadership, compliance, and stakeholder confidence.
Frequently Asked Questions — Financial Reporting
1. What is financial reporting, and why is it important?
Financial reporting is the process of preparing and communicating financial information—mainly through formal statements such as the statement of financial position and statement of profit or loss—so that users can understand an organisation’s performance and financial position. It is important because investors, lenders, regulators, and managers rely on this information to make economic decisions and to assess stewardship of resources.
2. How is financial reporting different from management accounting?
Financial reporting focuses on providing general-purpose financial statements for external users, prepared according to accounting standards and usually covering a past reporting period. Management accounting focuses on internal reports for managers, often forward-looking and customised, to support planning, control, and decision-making. Both rely on accounting data, but they serve different audiences and follow different rules.
3. What are the main financial statements produced in financial reporting?
The main financial statements are the statement of financial position (balance sheet), the statement of profit or loss and other comprehensive income, the statement of changes in equity, and the statement of cash flows. These are supported by notes that explain accounting policies, provide breakdowns, and disclose additional information needed to understand the numbers.
4. What are accounting standards, and why do they matter for financial reporting?
Accounting standards—such as International Financial Reporting Standards (IFRS) or national generally accepted accounting principles (GAAP)—provide detailed rules and principles on how to recognise, measure, present, and disclose items in financial statements. They matter because they promote consistency, comparability, and transparency, making it easier for users to interpret information across companies and across time.
5. What are the qualitative characteristics of useful financial information?
Useful financial information should be relevant and faithfully represent what it claims to depict. Relevance means it can influence decisions by helping users evaluate past, present, or future events. Faithful representation means information is complete, neutral, and free from error. Enhancing characteristics include comparability, verifiability, timeliness, and understandability.
6. What is the difference between accrual basis and cash basis in financial reporting?
Under the accrual basis, income and expenses are recognised when they are earned or incurred, not when cash is received or paid. This approach aims to match income with the costs used to generate it and is required by most financial reporting frameworks. Under the cash basis, transactions are recorded only when cash changes hands, which can be simpler but gives a less complete picture of performance and obligations.
7. How are assets and liabilities recognised and measured in financial reporting?
Assets are recognised when it is probable that future economic benefits will flow to the entity and the asset has a cost or value that can be measured reliably. Liabilities are recognised when there is a present obligation arising from past events that is expected to result in an outflow of resources. Depending on the standard, items may be measured at historical cost, amortised cost, current cost, or fair value, with additional rules for depreciation, impairment, and provisions.
8. What is fair value, and when is it used in financial reporting?
Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. It is used for many financial instruments and some non-financial assets, especially when the business model involves trading or when fair value provides more relevant information than historical cost.
9. Who uses financial reports, and how do they use them?
Key users include existing and potential investors, lenders, suppliers, employees, customers, regulators, and the wider public. They use financial reports to assess profitability, liquidity, solvency, and risk; to decide whether to buy, hold, or sell investments; to evaluate creditworthiness; to negotiate contracts; and to monitor compliance with laws and covenants.
10. What are some limitations of financial statements that students should be aware of?
Financial statements have limitations such as reliance on estimates and judgements, the use of historical costs in many areas, and the fact that they may not capture all intangibles like brand strength or organisational culture. They are also shaped by the chosen accounting policies and may not reflect non-financial factors such as environmental impact or social responsibility. Users must therefore interpret them critically and in context.
11. What skills are helpful for studying financial reporting at university?
Helpful skills include a solid grounding in basic accounting, comfort with algebra and spreadsheet work, and careful reading of technical standards. Just as important are logical reasoning, attention to detail, the ability to explain complex ideas clearly, and a willingness to work through structured problems step by step using examples and case studies.
12. How can learning financial reporting support my future career, even outside accounting?
Learning financial reporting teaches you how to read and interpret financial statements, understand the story behind the numbers, and recognise how accounting choices affect reported performance. These skills are valuable in roles across finance, management, consulting, policy, entrepreneurship, and any area where you need to evaluate organisations, projects, or investments.
Sharpen Your Reporting Skills: Q&A Practice
-
What is financial reporting?
Answer: Financial reporting is the process of preparing and presenting financial information about a company’s performance and position through documents such as balance sheets, income statements, and cash flow statements. -
How do balance sheets contribute to financial reporting?
Answer: Balance sheets provide a snapshot of a company’s financial position at a specific point in time by detailing its assets, liabilities, and equity, which helps stakeholders assess financial stability and resource allocation. -
What is the purpose of an income statement in financial reporting?
Answer: The income statement shows a company’s revenues, expenses, and profits over a period of time, enabling the evaluation of operational performance and profitability. -
How does a cash flow statement differ from other financial statements?
Answer: A cash flow statement tracks the inflow and outflow of cash, categorizing cash activities into operating, investing, and financing, which helps assess liquidity and cash management. -
Why is transparency important in financial reporting?
Answer: Transparency ensures that financial information is accurate and clear, building trust with investors, creditors, and regulators by providing a true picture of a company’s financial health. -
How do accounting principles like GAAP or IFRS affect financial reporting?
Answer: GAAP and IFRS provide standardized guidelines that ensure consistency, comparability, and reliability in financial reporting across different organizations and regions. -
What role do auditors play in the financial reporting process?
Answer: Auditors independently verify financial statements to ensure accuracy and compliance with accounting standards, which enhances the credibility and reliability of the reported information. -
How can financial reporting influence business decision-making?
Answer: Financial reporting provides key insights into a company’s performance and financial position, enabling managers and investors to make informed decisions regarding investments, financing, and strategic planning. -
What is the significance of the statement of retained earnings?
Answer: The statement of retained earnings shows how net income is distributed between dividends and retained earnings, reflecting the company’s reinvestment strategy and financial growth over time. -
How do cash flow statements help assess a company’s financial health?
Answer: Cash flow statements reveal the liquidity position by tracking cash inflows and outflows, helping stakeholders understand the company’s ability to meet short-term obligations and invest in future growth.
Beyond Compliance: Hard Questions in Reporting
-
How might the integration of technology, such as AI, change the future of financial reporting?
Answer: AI can automate data collection, error-checking, and analysis, leading to real-time, more accurate financial reports. This technology may reduce human error, lower costs, and provide deeper insights through predictive analytics, transforming traditional reporting practices. -
In what ways does transparent financial reporting impact investor confidence?
Answer: Transparent reporting builds trust by providing clear, reliable, and comprehensive financial data. Investors are more likely to invest in companies that demonstrate accountability and integrity, leading to higher market valuations and improved access to capital. -
How can financial reporting contribute to better corporate governance?
Answer: Accurate financial reporting ensures that all stakeholders have a clear understanding of a company’s financial performance and risks. This transparency supports better decision-making, accountability, and ethical behavior within the organization, strengthening corporate governance. -
What challenges do multinational companies face in maintaining consistent financial reporting standards?
Answer: Multinational companies must navigate different accounting standards, currency fluctuations, and regulatory environments. Harmonizing financial reports across regions requires robust internal controls and the adoption of global standards like IFRS to ensure consistency. -
How might emerging regulatory changes impact financial reporting practices in the near future?
Answer: New regulations can require additional disclosures, stricter compliance measures, and enhanced transparency. Companies may need to invest in advanced reporting systems and training to meet evolving standards and maintain stakeholder trust. -
In what ways does the accuracy of financial reporting affect a company’s strategic decision-making?
Answer: Accurate financial reporting provides a solid foundation for assessing performance, identifying trends, and forecasting future financial conditions. This information is critical for strategic planning, budgeting, and risk management, ultimately influencing long-term business success. -
How can the use of integrated reporting enhance traditional financial reporting practices?
Answer: Integrated reporting combines financial and non-financial information, offering a more comprehensive view of a company’s performance, including environmental, social, and governance factors. This holistic approach can improve stakeholder understanding and support sustainable business strategies. -
What role does financial reporting play in mitigating corporate fraud?
Answer: Robust financial reporting, combined with independent audits and internal controls, helps detect inconsistencies and irregularities that may indicate fraud. Transparent and timely reporting can serve as a deterrent to fraudulent activities by promoting accountability. -
How do advancements in cloud computing influence the speed and accessibility of financial reporting?
Answer: Cloud computing enables real-time data sharing, streamlined collaboration, and secure storage of financial information. This technology improves the speed of report generation and makes financial data more accessible to stakeholders, facilitating quicker decision-making. -
In what ways can financial reporting be used to predict future market trends?
Answer: Analyzing historical financial data and key performance indicators allows companies to identify patterns and trends. Predictive analytics and forecasting models built on accurate reporting can help anticipate market changes and guide strategic planning. -
How might the growing emphasis on sustainability influence financial reporting disclosures?
Answer: Companies are increasingly required to disclose environmental and social impacts. Sustainability reporting, integrated with traditional financial reporting, provides a more complete picture of a company’s overall performance and long-term viability, influencing investor and consumer decisions. -
What is the potential impact of blockchain technology on enhancing the reliability and transparency of financial reporting?
Answer: Blockchain technology offers a decentralized and immutable ledger that can record transactions securely and transparently. Its integration into financial reporting could reduce fraud, enhance auditability, and increase trust among stakeholders by providing verifiable financial records.
Working with the Numbers: Solving Financial Reporting Problems
-
A company reports total revenues of $2,000,000 and expenses of $1,500,000. Calculate the net income and profit margin percentage.
Solution: Net Income = Revenue – Expenses = $2,000,000 – $1,500,000 = $500,000Profit Margin = (Net Income / Revenue) × 100
Profit Margin = ($500,000 / $2,000,000) × 100 = 25% -
A business has assets of $5,000,000 and liabilities of $3,000,000. Calculate the equity.
Solution:Equity = Assets – Liabilities
Equity = $5,000,000 – $3,000,000 = $2,000,000 -
If a company’s current assets total $600,000 and its current liabilities are $300,000, what is the current ratio?
Solution:Current Ratio = Current Assets / Current Liabilities
Current Ratio = $600,000 / $300,000 = 2 -
A firm’s net income is $800,000 and its total revenue is $5,000,000. Calculate the net profit margin.
Solution:Net Profit Margin = (Net Income / Revenue) × 100
Net Profit Margin = ($800,000 / $5,000,000) × 100 = 16% -
A company’s return on equity (ROE) is 20% and its net income is $400,000. What is its average equity?
Solution: ROE = Net Income / Average EquityAverage Equity = Net Income / ROE
Average Equity = $400,000 / 0.20 = $2,000,000 -
If a firm’s cost of goods sold (COGS) is $3,000,000 and its average inventory is $500,000, what is the inventory turnover ratio?
Solution:Inventory Turnover = COGS / Average Inventory
Inventory Turnover = $3,000,000 / $500,000 = 6 -
A company issues bonds with a face value of $1,000,000 and a coupon rate of 5%. Calculate the annual interest payment.
Solution: Annual Interest Payment = Face Value × Coupon Rate = $1,000,000 × 0.05 = $50,000. -
If the earnings per share (EPS) is $2.50 and there are 400,000 shares outstanding, calculate the net income.
Solution: Net Income = EPS × Number of Shares = $2.50 × 400,000 = $1,000,000. -
A budgeting forecast projects a 10% increase in sales from $3,000,000. What is the expected sales figure?
Solution: Increase = 10% of $3,000,000 = 0.10 × $3,000,000 = $300,000
Expected Sales = $3,000,000 + $300,000 = $3,300,000. -
A company allocates 35% of its budget to marketing. If the total budget is $250,000, how much is spent on marketing?
Solution: Marketing Budget = 0.35 × $250,000 = $87,500. -
A firm experiences a 5% decrease in operating costs from $600,000. Calculate the new operating costs.
Solution: Decrease = 5% of $600,000 = 0.05 × $600,000 = $30,000
New Operating Costs = $600,000 – $30,000 = $570,000. -
If a company’s debt-to-equity ratio is 0.5 and its equity is $4,000,000, what is its total debt?
Solution: Debt-to-Equity Ratio = Debt / Equity
Debt = 0.5 × Equity = 0.5 × $4,000,000 = $2,000,000.