
Microeconomics explores the choices individuals and firms make when faced with limited resources. It analyzes how prices are determined, how goods and services are allocated, and how consumers and producers interact in markets. As a core branch of economics, microeconomics helps explain everyday decisions and policy outcomes at the most immediate level of economic activity.
Students of microeconomics gain insight into the foundational principles that govern supply and demand, price elasticity, and utility. This framework supports deeper studies in areas such as accounting, tax compliance and planning, and investment and portfolio management. The understanding of firm behavior and cost structures also plays a critical role in operations management and business analytics.
Microeconomic theories are essential when analyzing market structures, competition, and firm strategy. These topics are closely linked to studies in corporate law, mergers and acquisitions, and regulatory adherence. Meanwhile, data-driven decision-making benefits from proficiency in data analysis, statistics, and tools rooted in artificial intelligence and machine learning.
Although macroeconomics looks at the economy on a large scale, macroeconomic trends often emerge from micro-level decisions. Exploring the interplay between these levels enriches understanding in fields like operations research and emerging technologies. Moreover, analyzing consumer behavior and firm strategy contributes to evaluating trade regulations and the impact of globalization.
A deeper historical perspective is gained through studies such as financial history and industrial and technological history. These topics help contextualize how economic institutions evolved. Courses in curriculum design and business administration further equip learners with practical knowledge to apply microeconomic reasoning in educational and organizational contexts.
Ultimately, microeconomics offers critical tools for analyzing decisions at every level—from household consumption to firm investment and policy formation. It prepares students to engage effectively in both academic and applied fields, such as international business and fiscal policy analysis, and is indispensable for anyone pursuing studies in business, economics and law.
Definition of Microeconomics
Microeconomics is the study of how individuals and firms make choices about the allocation of scarce resources. It explores the dynamics of supply and demand, market structures, and the behavior of economic agents under different conditions.
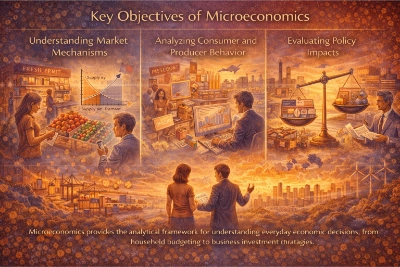
Key Objectives of Microeconomics:
- Understanding Market Mechanisms: Explaining how prices are determined and resources are allocated in competitive markets.
- Analyzing Consumer and Producer Behavior: Examining how individuals and firms respond to changes in prices, income, and market conditions.
- Evaluating Policy Impacts: Assessing the effects of taxation, subsidies, and regulations on economic activity.
Microeconomics provides the analytical framework for understanding everyday economic decisions, from household budgeting to business investment strategies.
Interactive Consumer Surplus & Elasticity Simulator
Adjust market price (P) and maximum willingness to pay (Choke Price) to calculate consumer surplus, quantity demanded, and total revenue live on the graph.
Key Topics in Microeconomics
1. Supply and Demand
- Definition: Supply and demand are the fundamental forces that determine prices and quantities in a market.
- Key Components:
- Law of Demand: As prices decrease, the quantity demanded increases, ceteris paribus.
- Law of Supply: As prices increase, the quantity supplied rises, ceteris paribus.
- Market Equilibrium: The point where supply equals demand, determining the market price and quantity.
- Elasticity: Measuring the responsiveness of demand or supply to changes in price, income, or other factors.
- Applications:
- Setting optimal pricing strategies for businesses.
- Predicting the effects of changes in production costs or consumer preferences on market outcomes.
- Examples:
- A smartphone manufacturer increasing supply in response to rising demand for its latest model.
- An agricultural market experiencing price fluctuations due to changes in weather conditions affecting supply.
2. Consumer Behavior
- Definition: The study of how individuals make decisions to maximize utility (satisfaction) given their budget constraints.
- Key Components:
- Utility Maximization: Choosing a combination of goods and services that provides the greatest satisfaction.
- Indifference Curves: Representing combinations of goods that yield the same level of utility.
- Budget Constraints: The trade-offs consumers face due to limited income.
- Applications:
- Designing marketing strategies that align with consumer preferences.
- Assessing the impact of price changes on consumer purchasing behavior.
- Examples:
- A family reallocating its budget to spend more on groceries as food prices rise.
- A consumer choosing between buying a high-quality product or a cheaper alternative based on perceived value.
3. Market Structures
- Definition: The classification of markets based on the level of competition and the behavior of firms.
- Key Components:
- Perfect Competition: A market with many buyers and sellers, where no single entity can influence prices.
- Monopoly: A market dominated by a single seller with significant control over prices.
- Oligopoly: A market with a few dominant firms that influence each other’s decisions.
- Monopolistic Competition: A market where many firms sell similar but differentiated products.
- Applications:
- Evaluating the pricing power of firms under different market conditions.
- Analyzing the effects of mergers and acquisitions on market competition.
- Examples:
- A utility company operating as a natural monopoly due to high infrastructure costs.
- Airlines engaging in price wars in an oligopolistic market structure.
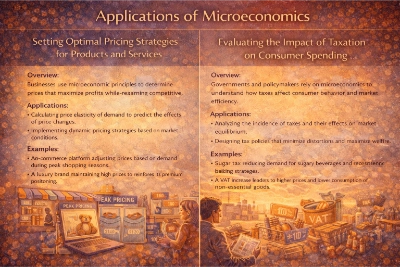
Applications of Microeconomics
1. Setting Optimal Pricing Strategies for Products and Services
- Overview: Businesses use microeconomic principles to determine prices that maximize profits while remaining competitive.
- Applications:
- Calculating price elasticity of demand to predict the effects of price changes.
- Implementing dynamic pricing strategies based on market conditions.
- Examples:
- An e-commerce platform adjusting prices based on demand during peak shopping seasons.
- A luxury brand maintaining high prices to reinforce its premium positioning.
2. Evaluating the Impact of Taxation on Consumer Spending
- Overview: Governments and policymakers rely on microeconomics to understand how taxes affect consumer behavior and market efficiency.
- Applications:
- Analyzing the incidence of taxes and their effects on market equilibrium.
- Designing tax policies that minimize distortions and maximize welfare.
- Examples:
- A sugar tax reducing demand for sugary beverages and encouraging healthier choices.
- A VAT increase leading to higher prices and lower consumption of non-essential goods.
Examples of Microeconomics in Action
1. A Restaurant Adjusting Prices Based on Changes in Food Costs
- Scenario: A restaurant experiences rising costs for ingredients due to supply chain disruptions.
- Outcome: The restaurant raises menu prices while offering promotions on high-margin items to maintain profitability and customer satisfaction.
2. Analyzing the Effect of Subsidies on Renewable Energy Adoption
- Scenario: A government introduces subsidies for solar panel installations to encourage renewable energy use.
- Outcome: Increased adoption of solar panels by households and businesses, reducing dependence on fossil fuels and lowering carbon emissions.
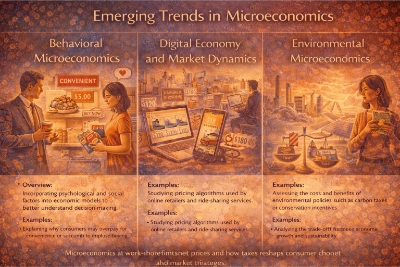
Emerging Trends in Microeconomics
Behavioral Microeconomics
- Incorporating psychological and social factors into economic models to better understand decision-making.
- Examples: Explaining why consumers may overpay for convenience or succumb to impulse buying.
Digital Economy and Market Dynamics
- Analyzing the impact of digital platforms, gig economies, and e-commerce on traditional market structures.
- Examples: Studying pricing algorithms used by online retailers and ride-sharing services.
Environmental Microeconomics
- Assessing the costs and benefits of environmental policies, such as carbon taxes or conservation incentives.
- Examples: Analyzing the trade-offs between economic growth and sustainability.
Challenges in Microeconomics
Market Failures
- Addressing situations where markets fail to allocate resources efficiently, such as negative externalities or underprovided public goods.
Income Inequality
- Examining how market forces contribute to wealth disparities and exploring potential policy interventions.
Technological Disruption
- Adapting economic models to account for rapid shifts in automation, consumer data privacy, and digital labor platforms.
Globalization and Trade
- Understanding how international trade policy and cross-border supply networks affect local micro-markets.
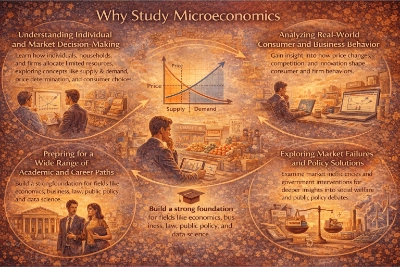
Why Study Microeconomics
Understanding Individual and Market Decision-Making
Microeconomics focuses on how individuals, households, and firms make decisions about the allocation of limited resources. It explores concepts such as supply and demand, price determination, consumer choice, and production costs. For students preparing for university, studying microeconomics provides a clear framework for understanding how markets operate and how economic choices are made at the most fundamental level.
Analyzing Real-World Consumer and Business Behavior
By studying microeconomics, students gain insight into how consumers respond to price changes, how businesses set prices and output levels, and how market competition shapes innovation and efficiency. These concepts are directly relevant to everyday experiences and help students build practical thinking skills that are useful in business, marketing, finance, and management courses at university.
Developing Logical, Mathematical, and Graphical Skills
Microeconomics involves modeling decision-making using equations, graphs, and logical reasoning. Students learn how to interpret and construct supply and demand curves, identify equilibrium points, and evaluate market outcomes. These skills strengthen mathematical literacy and critical analysis, both of which are essential for success in quantitative university subjects such as economics, business analytics, and data science.
Exploring Market Failures and Policy Solutions
Microeconomics also addresses cases where markets do not function efficiently, such as externalities, public goods, and monopolies. Students learn how government intervention, such as taxes, subsidies, or regulation, can correct market failures. This understanding fosters deeper engagement with debates around social welfare, environmental sustainability, and income distribution—key topics in law, politics, and public policy studies at the university level.
Preparing for a Wide Range of Academic and Career Paths
A background in microeconomics supports future study in economics, finance, business, law, international development, and public administration. The ability to think systematically about incentives, trade-offs, and decision-making is highly valued across disciplines and professions. For students preparing for university, microeconomics provides a rigorous and relevant foundation that enhances both academic readiness and career flexibility.
Microeconomics: Conclusion
Microeconomics is an essential discipline that provides insights into the decision-making processes of individuals, households, and firms. By focusing on key areas such as supply and demand, consumer behavior, and market structures, microeconomics helps businesses optimize pricing strategies, policymakers design effective regulations, and consumers make informed choices. As new challenges and opportunities arise in a globalized and technology-driven world, microeconomics continues to evolve, offering tools to navigate complexity and drive economic progress. Its principles remain integral to understanding and improving the economic well-being of individuals and society.
Economics Overview Hub
Return to the foundational hub exploring how scarcity and trade-offs shape overall human decisions.
Return to Economics →
Macroeconomics Subhub
Explore systemic national trends, interest rates, inflation measures, and aggregate GDP performance.
Explore Macroeconomics →
Policy Analysis Subhub
Learn how microeconomic market models evaluate government regulations, tax policy, and subsidies.
Explore Policy Analysis →
Frequently Asked Questions – Microeconomics
What is microeconomics in simple terms?
Microeconomics is the branch of economics that focuses on individual decision-makers—consumers, households, and firms—and how they allocate scarce resources within specific markets to satisfy needs and maximize welfare or profit.
How does microeconomics differ from macroeconomics?
While macroeconomics looks at economy-wide phenomena like national income, inflation, and unemployment, microeconomics zooms in on the behavior of individual market participants, product pricing, elasticity, and specific industry structures.
What are the four main market structures studied in microeconomics?
The four primary market structures are Perfect Competition (many sellers, identical products), Monopoly (one single seller), Oligopoly (a few dominant firms), and Monopolistic Competition (many sellers with differentiated products).
Why is price elasticity of demand important for businesses?
Price elasticity measures how sensitive consumers are to price changes. Knowing whether demand is elastic or inelastic allows businesses to predict how raising or lowering prices will impact total revenue and sales volume.
What is a market failure, and how can government intervene?
A market failure occurs when a free market fails to allocate resources efficiently, resulting in welfare loss (e.g., pollution externalities or monopolies). Governments intervene using corrective taxes, subsidies, price controls, or public provision.
Microeconomics Practice & Quantitative Assessment Module
Section 1: Foundational Review Questions
- What is microeconomics and why is it important?
Answer: Microeconomics studies the behavior of individual economic agents—households, firms, and markets—and how they interact to allocate scarce resources. It is important because it helps explain decision-making processes, market outcomes, and the distribution of goods and services in the economy. - How do demand and supply determine market equilibrium?
Answer: Demand and supply interact to set the market price and quantity. Equilibrium is reached when the quantity demanded equals the quantity supplied. At this point, there is no incentive for the price to change, ensuring that resources are allocated efficiently. - What is price elasticity of demand and how is it calculated?
Answer: Price elasticity of demand measures the responsiveness of the quantity demanded to a change in price. It is calculated using the formula: Elasticity = (Percentage Change in Quantity Demanded) / (Percentage Change in Price). This indicator helps firms predict consumer behavior and set optimal pricing strategies. - How does consumer surplus illustrate the benefits consumers receive in a market?
Answer: Consumer surplus is the difference between the maximum price consumers are willing to pay and the market price. It represents the net benefit consumers gain from purchasing a product at a lower price, reflecting overall consumer welfare. - What role does opportunity cost play in microeconomic decision-making?
Answer: Opportunity cost is the value of the next best alternative forgone when making a choice. It is crucial in microeconomic decision-making because it ensures that scarce resources are allocated to their most valued uses, helping individuals and firms optimize outcomes. - How can changes in market conditions affect equilibrium price and quantity?
Answer: Shifts in either the demand or supply curves—caused by factors such as changes in income, tastes, technology, or input prices—will alter the equilibrium price and quantity. An increase in demand raises both price and quantity, while an increase in supply lowers price and increases quantity. - What is the significance of marginal analysis in microeconomics?
Answer: Marginal analysis examines the additional benefits and costs of a decision. By evaluating incremental changes, consumers and firms can determine the optimal level of production or consumption, ensuring efficient resource allocation. - How do firms use cost curves to make production decisions?
Answer: Firms analyze cost curves—such as average total cost, marginal cost, and average variable cost—to determine the most cost-efficient level of production. By comparing marginal cost with marginal revenue, firms decide whether to expand or reduce output to maximize profit. - What factors can lead to market failures in microeconomics?
Answer: Market failures occur when free markets do not allocate resources efficiently. Factors such as externalities, public goods, information asymmetry, and monopolistic practices can lead to market failures, prompting the need for government intervention. - How do consumer preferences and income levels affect demand?
Answer: Consumer preferences determine the desirability of goods, while income levels affect purchasing power. Changes in either factor shift the demand curve, altering the equilibrium price and quantity in the market.
Section 2: Analytical & Thought-Provoking Scenarios (Collapsible)
1. How might digital marketplaces and e-commerce platforms influence microeconomic consumer behavior?
2. In what ways can microeconomic theory explain the phenomenon of price discrimination?
3. How does the concept of elasticity affect the strategies firms use to set prices?
4. How can the concept of marginal cost be used to explain a firm’s decision to increase or decrease production?
5. What is the impact of consumer surplus on market efficiency, and how can it be quantified?
6. How might shifts in supply and demand curves affect consumer and producer surpluses in a competitive market?
7. How does the concept of opportunity cost apply to resource allocation in competitive markets?
8. What are the long-term effects of persistent inflation on consumer purchasing power and economic growth?
9. How can elasticity be used to predict changes in market outcomes following a tax increase?
10. How might a subsidy affect market equilibrium and overall economic welfare?
11. What are the macroeconomic implications of prolonged low unemployment on wage growth and inflation?
12. How do changes in government spending and taxation influence aggregate demand?
Section 3: Numerical Problems & Applied Calculation Solutions
-
Problem 1: Demand and Supply Equilibrium & Producer Surplus
A market has a demand function Qd = 250 – 3P and a supply function Qs = 2P + 50. Calculate the equilibrium price (P*) and quantity (Q*), and compute producer surplus (assuming supply intercept at P = -25, so minimum supply price at Q=0 is P = 25 for non-negative production).
Solution & Step-by-Step Calculation:Step 1: Set Qd = Qs ⇒ 250 – 3P = 2P + 50.
250 – 50 = 5P ⇒ 200 = 5P ⇒ P* = $40.
Step 2: Substitute P* = 40 into demand equation:
Q* = 250 – 3(40) = 250 – 120 = 130 units.
Step 3: Calculate Producer Surplus (PS):
Minimum supply price (where Qs = 0): 0 = 2P – 50 (or 2P = 50 ⇒ Pmin = $25).
PS = 0.5 × (Equilibrium Price – Pmin) × Equilibrium Quantity
PS = 0.5 × ($40 – $25) × 130 = 0.5 × 15 × 130 = $975. -
Problem 2: Point Elasticity & Total Revenue Change
Given a demand function Q = 300 – 5P, calculate the point price elasticity of demand at P = $40. Then determine the exact percentage change in total revenue if price increases from $40 to $42.
Solution & Step-by-Step Calculation:Step 1: At P = 40, Q = 300 – 5(40) = 100 units.
Derivative dQ/dP = -5.
Point Elasticity = (dQ/dP) × (P / Q) = -5 × (40 / 100) = -2.0 (Elastic).
Step 2: Calculate Total Revenues (TR):
TR1 at P = 40: 40 × 100 = $4,000.
At P = 42: Q = 300 – 5(42) = 90 units.
TR2 at P = 42: 42 × 90 = $3,780.
Step 3: Percentage Change in TR = [($3,780 – $4,000) / $4,000] × 100 = -5.50%. -
Problem 3: Consumer Surplus Calculation
Given the demand function Q = 500 – 10P, calculate the consumer surplus when the equilibrium market price is $30.
Solution & Step-by-Step Calculation:Step 1: Find Choke Price (where Q = 0): 0 = 500 – 10P ⇒ Pchoke = $50.
Step 2: Find Q* at P = 30: Q = 500 – 10(30) = 200 units.
Step 3: Consumer Surplus = 0.5 × (Pchoke – P*) × Q*
CS = 0.5 × (50 – 30) × 200 = 0.5 × 20 × 200 = $2,000. -
Problem 4: Impact of a Production Subsidy
Market demand is Qd = 400 – 4P and supply is Qs = 2P – 50. Calculate initial equilibrium. Then, if government provides a $10 per unit subsidy to producers, calculate the new equilibrium price paid by consumers and new quantity.
Solution & Step-by-Step Calculation:Step 1 (Initial Equilibrium): 400 – 4P = 2P – 50 ⇒ 450 = 6P ⇒ P* = $75, Q* = 100.
Step 2 (Post-Subsidy Supply): Producers receive (P + 10).
New Supply Qs‘ = 2(P + 10) – 50 = 2P – 30.
Step 3 (New Equilibrium): 400 – 4P = 2P – 30 ⇒ 430 = 6P ⇒ Pconsumer = $71.67.
New Quantity Q’ = 400 – 4(71.67) = 113.33 units. -
Problem 5: Per-Unit Tax Incidence Calculation
Market demand is Qd = 600 – 6P and supply is Qs = 3P – 50. If a $5 per-unit tax is imposed on producers, calculate the new consumer price and consumer tax incidence per unit.
Solution & Step-by-Step Calculation:Step 1 (Pre-tax Equilibrium): 600 – 6P = 3P – 50 ⇒ 650 = 9P ⇒ P1 = $72.22.
Step 2 (Post-tax Supply): Supply with $5 tax: Qs‘ = 3(P – 5) – 50 = 3P – 65.
Step 3 (New Consumer Price): 600 – 6P = 3P – 65 ⇒ 665 = 9P ⇒ Pconsumer = $73.89.
Step 4 (Tax Incidence on Consumer): $73.89 – $72.22 = $1.67 per unit (33.4% of tax). -
Problem 6: Price Elasticity & Unitary Demand TR Impact
For demand Q = 800 – 8P, calculate point elasticity at P = $50. Calculate total revenue at P = 50 and P = 55.
Solution & Step-by-Step Calculation:Step 1: At P = 50, Q = 800 – 8(50) = 400 units.
Point Elasticity = -8 × (50 / 400) = -1.0 (Unitary Elasticity).
Step 2: TR at P = 50: 50 × 400 = $20,000.
At P = 55: Q = 800 – 8(55) = 360 units.
TR at P = 55: 55 × 360 = $19,800.
Step 3: TR decreases by $200 (-1.0%). -
Problem 7: Large-Scale Consumer Surplus Evaluation
Demand curve is Q = 1,000 – 5P. Determine consumer surplus when market price is $100.
Solution & Step-by-Step Calculation:Step 1: Choke Price (Q = 0): 1,000 – 5P = 0 ⇒ Pchoke = $200.
Step 2: Quantity at P = 100: Q = 1,000 – 5(100) = 500 units.
Step 3: CS = 0.5 × ($200 – $100) × 500 = 0.5 × 100 × 500 = $25,000. -
Problem 8: Price Ceiling & Deadweight Loss Calculation
Demand is Q = 700 – 7P and supply is Q = 4P – 50. If government imposes a price ceiling of $80, calculate quantity transacted and deadweight loss.
Solution & Step-by-Step Calculation:Step 1 (Pre-ceiling Equilibrium): 700 – 7P = 4P – 50 ⇒ 750 = 11P ⇒ P* = $68.18, Q* = 222.73 units.
Step 2 (At Price Ceiling $80): Note that $80 is ABOVE equilibrium price $68.18. A price ceiling set above equilibrium is non-binding.
Step 3: Market operates at equilibrium price $68.18, quantity transacted = 222.73 units, and Deadweight Loss = $0. -
Problem 9: Midpoint (Arc) Elasticity Calculation
Price increases from $40 to $50, causing quantity demanded to fall from 200 units to 160 units. Calculate Arc Price Elasticity of Demand.
Solution & Step-by-Step Calculation:Step 1: Delta Q = 160 – 200 = -40; Average Q = (200 + 160)/2 = 180. % Delta Q = -40 / 180 = -22.22%.
Step 2: Delta P = 50 – 40 = 10; Average P = (40 + 50)/2 = 45. % Delta P = 10 / 45 = 22.22%.
Step 3: Arc Elasticity = -22.22% / 22.22% = -1.0. -
Problem 10: Opportunity Cost in Manufacturing Allocation
A factory can produce 1,200 units of Product A or 800 units of Product B per day. If it produces 900 units of Product A, calculate the opportunity cost in terms of Product B foregone.
Solution & Step-by-Step Calculation:Step 1: Trade-off ratio = 800 B / 1,200 A = 0.6667 units of B per unit of A.
Step 2: Foregone units of A capacity = 1,200 – 900 = 300 units of A.
Step 3: Opportunity cost in B = 300 × 0.6667 = 200 units of Product B foregone.