
Corporate Restructuring and Strategic Consolidation Processes
Mergers and Acquisitions (M&A) – What It is All About
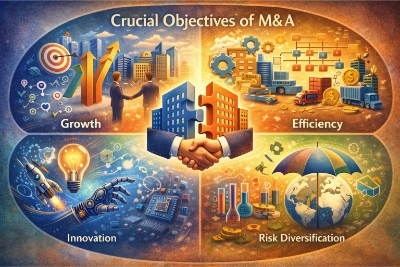
Crucial Objectives of M&A:
Growth & Expansion
Accelerates market access, expands customer bases, and boosts market share faster than organic growth.
Operational Efficiency
Captures economies of scale, eliminates redundant departments, and optimizes supply chain operations.
Innovation & Tech Access
Acquires proprietary technology, R&D pipelines, specialized talent, and patents to stay ahead.
Risk Diversification
Spreads risk across geographic markets, product lines, and revenue streams to buffer economic shifts.
- Growth: One of the most prominent reasons organizations pursue mergers and acquisitions is to accelerate growth. Rather than relying solely on organic expansion—such as increasing sales or opening new branches—M&A allows companies to immediately gain access to established markets, customer bases, and distribution networks. This can be particularly beneficial when entering a new region or market segment where building a presence from the ground up would be slow, costly, or uncertain. Through strategic consolidation, companies can grow their market share, eliminate key competitors, and expand their influence across different verticals. Growth-focused deals often target firms with complementary products or services that enhance the acquirer’s existing portfolio. In many cases, this objective also includes acquiring brand recognition, local market insights, and operational infrastructure that would otherwise take years to develop internally.
- Efficiency: Merger and acquisition activity is often aimed at creating operational synergies—combining two or more entities in ways that reduce costs and enhance productivity. By eliminating overlapping departments, consolidating supply chains, and integrating IT systems, organizations can streamline operations and significantly reduce redundancy. Economies of scale are a central driver here. A larger combined entity can often negotiate better terms with suppliers, reduce fixed overhead, and consolidate administrative functions like human resources, finance, and procurement. Efficiency-driven M&A deals typically involve detailed integration planning to ensure that the resulting organization runs smoothly and efficiently post-merger.
- Innovation: In today’s technology-driven economy, access to intellectual property and research capabilities is a key motivator for acquisition. Organizations may target startups or research-intensive firms to acquire proprietary technologies, patents, talent, or R&D pipelines that can significantly enhance innovation capacity. These innovation-focused M&A strategies help accelerate product development, improve competitive positioning, and reduce time-to-market. Particularly in sectors like biotech, software, and advanced manufacturing, acquiring a company with strong innovation assets can be a faster and less risky path to modernization than building capabilities in-house. Innovation-driven deals are not limited to technology. They may also involve acquiring companies with unique customer experience models, sustainable practices, or agile business processes that can be adopted and scaled across the acquiring organization.
- Risk Diversification: Another important objective of M&A is to reduce overall organizational risk. This is often achieved by diversifying across markets, industries, or revenue streams. For example, a company heavily reliant on one geographic region may acquire a firm in another part of the world to hedge against local economic downturns or regulatory shifts. Likewise, an organization that depends on a single product category may seek to acquire a company with a different but complementary line of products, helping reduce exposure to market volatility or consumer behavior changes. In regulated industries, diversification through M&A can also provide access to new licensing regimes or enable better compliance risk management. Well-executed diversification strategies through M&A enhance resilience, support long-term stability, and allow firms to respond more effectively to disruptions and emerging trends.
Building Blocks of Mergers and Acquisitions
Due Diligence: Uncovering Risks, Revealing Potential
Definition: Due diligence is the investigative journey a company embarks upon before committing to a merger or acquisition. It is the act of lifting the veil—financially, legally, and operationally—to understand exactly what is being acquired. This process is not just about verifying facts but about understanding the soul and structure of the target entity. It asks: What lies beneath the surface? What promises or perils await?
Key Features:
- Financial Due Diligence: Digs deep into balance sheets, cash flow reports, debt levels, tax obligations, and profit margins to confirm that financial health reflects reality.
- Legal Due Diligence: Scrutinizes commercial contracts, regulatory compliance, intellectual property ownership, and pending or potential litigation risks.
- Operational Due Diligence: Evaluates supply chain resilience, production facilities, IT systems, management structures, and workforce retention risks.
Applications & Examples: Exposes hidden liabilities like environmental fines or patent flaws. For instance, a tech giant verifies whether a target startup holds clean, unencumbered patent titles before purchase, or a buyer discovers pending environmental compliance violations during plant inspection.
Transaction Structuring: Designing the Framework of the Deal
Definition: Structuring a deal defines how the acquisition will unfold legally and financially. Each element is negotiated to balance risk, tax efficiency, and control between buyer and seller.
Key Features:
- Deal Types:
- Stock Purchase: Buyer acquires company shares, inheriting all assets and liabilities intact.
- Asset Purchase: Buyer selects specific assets (equipment, patents, contracts) and leaves behind undesired debts or liabilities.
- Merger: Fusion of two entities into a single corporate structure under statutory merger laws.
- Valuation Methods: Applies Discounted Cash Flow (DCF), Comparable Company Analysis, and Precedent Transactions to establish fair purchase prices.
- Contractual Agreements: Incorporates definitive Purchase Agreements, Shareholder Rights, Non-Compete Agreements, and Executive Employment Retention terms.
Applications & Examples: Utilizes earn-out contingency structures to tie payouts to future profit targets, or structures reverse mergers for private tech firms entering public equity markets.
Post-Merger Integration: Creating Harmony After the Deal
Definition: Post-merger integration is the strategic aligning of cultures, operating software, organizational hierarchies, and commercial workflows once legal contracts are signed.
Key Features:
- Cultural Integration: Addresses organizational friction, leadership styles, and communication norms to retain key talent and build team trust.
- Operational Alignment: Merges IT platforms, eliminates redundant departmental functions, and unifies logistics and procurement systems.
- Regulatory Compliance: Ensures continuous adherence to corporate, environmental, labor, and tax regulations post-closing.
Real-World Dimensions of Mergers and Acquisitions
Facilitating Cross-Border Mergers Between Multinational Companies
- Requires navigating dual legal, foreign investment review (e.g., CFIUS), and multi-currency tax frameworks.
- Demands cross-cultural leadership alignment and standardized global reporting structures.
- Example: A German automobile manufacturer merging with a South Korean battery supplier, requiring alignment of EU and Asian environmental and automotive safety regulations.
Structuring Asset Purchases for Strategic Growth
- Provides precision by acquiring key revenue-generating assets while insulating the buyer from legacy litigation or debt.
- Ideal for buying distressed corporate divisions out of bankruptcy or restructuring proceedings.
- Example: A retail group purchasing distribution centers and fleet vehicles from a regional competitor without assuming lease liabilities or corporate debt.
Stories of Mergers and Acquisitions in Motion
Legal Support for a Pharmaceutical Company Acquiring a Biotech Startup
Managing a Merger Between Two Competing Firms in the Automotive Industry
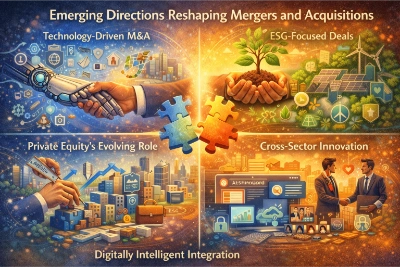
Emerging Directions Reshaping Mergers and Acquisitions
Technology as a Catalyst for Strategic Acquisitions
Companies prioritize acqui-hiring software engineering teams, AI platforms, and cloud databases to accelerate digital transformation over traditional physical expansion.Sustainability and Social Values Steering M&A Choices
ESG due diligence evaluates target carbon footprints, labor standards, and green technology capabilities before determining deal valuations.Private Equity’s Expanding Influence and Evolving Role
PE sponsors utilize buy-and-build strategies, operational restructuring, and specialized capital funds to optimize underperforming assets.Convergence of Sectors Creating Hybrid Business Models
Cross-sector consolidation—such as tech firms acquiring healthcare providers—blends distinct commercial capabilities into unified digital ecosystems.Digitally Intelligent Post-Merger Integration
AI analytics and cloud platforms monitor real-time workforce sentiment, supply chain synergy tracking, and cybersecurity integration metrics post-closing.
Challenges in M&A
Regulatory Barriers Across Borders and Bureaucracies
When Cultures Collide: The Invisible Challenge of Integration
The Tension of Value: Navigating Divergent Perceptions
Unlocking the Promise: The Elusive Art of Realizing Synergies
Stakeholder Resistance: Navigating the Human Undercurrents
Interactive Tool: M&A Synergy & Valuation Model Calculator
Evaluate combined corporate valuation, financial synergy gains, and post-merger earnings impact using standard Discounted Cash Flow and Synergy mechanics.
Why Mergers and Acquisitions Matter to Future Thinkers
The Ongoing Relevance of Mergers and Acquisitions
Frequently Asked Questions – Mergers and Acquisitions (M&A)
What are mergers and acquisitions (M&A) in simple terms?
Mergers and acquisitions are transactions in which companies join together or one company buys another. A merger usually means two companies combine to form a new larger entity, while an acquisition means one company takes control of another by buying its shares or assets.
Why do companies engage in mergers and acquisitions?
Companies pursue M&A to grow faster, enter new geographic markets, acquire technologies or brand assets, achieve economies of scale, reduce operational redundancies, or diversify commercial risks.
How are mergers and acquisitions related to corporate law?
Corporate law provides the legal framework governing how deals are structured, shareholder approvals, directors’ fiduciary duties, takeover regulations, and compliance with statutory filing requirements.
What is the difference between a share purchase and an asset purchase?
In a share purchase, the buyer acquires company shares and inherits all liabilities and assets. In an asset purchase, the buyer selects specific assets and liabilities, leaving unwanted debts with the seller.
What is due diligence in an M&A transaction?
Due diligence is a comprehensive investigation of a target company’s financial records, legal liabilities, contracts, IP assets, and operational risks prior to finalizing a transaction contract.
What role do corporate lawyers play in mergers and acquisitions?
Corporate lawyers design deal structures, conduct legal due diligence, draft purchase agreements, navigate regulatory approvals, advise on fiduciary duties, and manage closing procedures.
How are shareholders protected in M&A deals?
Shareholders are protected through securities laws requiring detailed disclosures, mandatory voting thresholds for major transactions, appraisal rights, and legal duties requiring directors to act in good faith.
What are hostile takeovers and how do they differ from friendly deals?
In a friendly deal, both boards negotiate mutually. In a hostile takeover, the acquirer bypassing target board approval by making tender offers directly to shareholders or launching proxy contests.
What risks commonly arise in mergers and acquisitions?
Key risks include overpaying due to flawed valuations, failing to achieve operational synergies, cultural integration friction, antitrust regulatory blocks, and key employee turnover.
Which school subjects provide a good foundation for studying M&A?
Helpful foundational subjects include economics, accounting, mathematics, corporate law, business administration, and strategic management.
Interactive Review Questions
Toggle each box below to reveal detailed explanations for core M&A concepts.
Why do acquirers often prefer an asset purchase over a stock purchase in distressed transactions?
What is the primary operational difference between cost synergies and revenue synergies?
How does an earn-out structure help resolve valuation disputes between buyers and sellers?
Comprehensive Practice & Mastery Module
Section 1: Foundational Concept Review Questions
-
What are the two fundamental legal structures for combining corporate control in M&A?
Answer: Stock Purchases (acquiring ownership equity/shares) and Asset Purchases (acquiring specific physical or intangible corporate assets). -
What primary objective drives operational cost synergies in horizontal mergers?
Answer: Capturing economies of scale, eliminating redundant corporate functions (HR, legal, accounting), and streamlining supply chain operations to lower unit costs. -
What critical process must an acquiring firm perform prior to signing a definitive acquisition contract?
Answer: Comprehensive Due Diligence across financial, legal, operational, tax, and environmental domains. -
What role do regulatory antitrust agencies play in reviewing large M&A transactions?
Answer: They evaluate whether proposed consolidations create unlawful market monopolies or substantially reduce competition, issuing blocks or requiring structural asset divestitures. -
What is an “earn-out” provision in an acquisition contract?
Answer: A contractual mechanism where part of the purchase price is paid conditionally after closing based on the target company hitting specified financial performance milestones. -
How does a reverse merger differ from a traditional initial public offering (IPO)?
Answer: A private operating company acquires a public shell company, allowing it to become publicly traded faster and with fewer underwriting steps than a conventional IPO. -
What is a hostile takeover?
Answer: An acquisition attempt pursued without the approval or endorsement of the target company’s board of directors, often through direct tender offers to shareholders. -
What is the function of an Integration Management Office (IMO) post-acquisition?
Answer: An IMO manages the operational execution, platform unification, cultural alignment, and tracking of synergy milestones across combined business units.
Section 2: Analytical & Scenario-Based Thought Questions
-
A technology conglomerate acquires a high-growth AI startup for a 50% premium over market value. Analyze why aggressive valuation premiums can lead to impairment charges if post-merger integration fails.
Answer: High premiums create significant “goodwill” assets on balance sheets. If the acquirer fails to realize expected revenue synergies or key engineering talent leaves due to cultural clash, the future cash flows fall short, forcing accounting goodwill write-downs and harming share price. -
Compare the legal exposure of an acquiring firm in a stock purchase versus an asset purchase when hidden environmental contamination is discovered post-closing.
Answer: In a stock purchase, the acquirer assumes the target entity as a whole, taking on full legal liability for past environmental contamination. In an asset purchase, liability can be contractually excluded, leaving pre-existing liabilities with the seller unless environmental statutes (like Superfund laws) impose successor liability. -
During a cross-border merger between a European consumer brand and a US distributor, regulatory agencies in both regions demand conflicting structural remedies. Evaluate strategies legal teams can deploy to save the transaction.
Answer: Legal teams can negotiate targeted regional divestitures, carve out conflicting business segments into independent licensed entities, or propose behavioral commitments (such as open licensing or price caps) to satisfy specific regulatory watchdogs. -
Why do ESG (Environmental, Social, Governance) factors increasingly drive deal abandonment during M&A due diligence?
Answer: Uncovered ESG liabilities—such as poor carbon emissions compliance, labor exploitation, or weak governance—pose severe reputational damage, regulatory fines, and future capital discount risks that undermine overall investment theses. -
Analyze how private equity buy-and-build strategies differ from strategic corporate acquisitions in their approach to long-term operational hold periods.
Answer: Strategic corporate acquirers usually seek permanent operational integration and long-term commercial synergy. Private equity sponsors typically operate on 3-to-7-year hold cycles, focusing on rapid margin improvement, operational leverage, and exit multiples through resale or IPO. -
Why is cultural due diligence as critical as financial due diligence in preventing post-merger value destruction?
Answer: Misaligned corporate cultures cause communication breakdowns, key talent attrition, employee resistance, and lost productivity, which directly derail the operational synergies required to justify acquisition costs. -
How do poison pills and defensive governance provisions protect target shareholders during hostile takeover bids?
Answer: Poison pills allow existing shareholders to buy additional stock at a discount when an unapproved acquirer crosses an ownership threshold, diluting the bidder’s stake and forcing them to negotiate directly with the target board.
Section 3: Mathematical Calculations & Numerical Problems
-
Acquisition Purchase Price & Premium Calculation: Company A agrees to acquire Target Company B. Target B has 10,000,000 outstanding shares trading at $25 per share. Company A offers a 30% acquisition premium. Calculate (a) the offer price per share and (b) the total purchase price paid for Target B.
Answer: (a) Offer Price per Share = Base Price × (1 + Premium Rate) = $25 × (1 + 0.30) = $32.50 per share.
(b) Total Purchase Price = Shares Outstanding × Offer Price = 10,000,000 × $32.50 = $325,000,000. -
Net Present Value (NPV) of M&A Cost Synergies: An acquisition generates $20,000,000 in annual post-tax cost synergies. If these synergies are projected to continue for 5 years and the acquirer’s discount rate is 8%, calculate the Present Value (PV) of these total synergies.
Answer:PV = ∑t=15 [ C / (1 + r)t ]
Year 1: $20M / 1.081 = $18.518M
Year 2: $20M / 1.082 = $17.147M
Year 3: $20M / 1.083 = $15.877M
Year 4: $20M / 1.084 = $14.701M
Year 5: $20M / 1.085 = $13.612M
Total PV of Synergies = $79.855M (or $79,855,000). -
Accretion/Dilution Earnings Per Share (EPS) Analysis: Acquirer A (Net Income $100M, 20M shares, EPS $5.00) acquires Target B (Net Income $30M). Acquirer A issues 5M new shares to fund the acquisition. Calculate the combined post-merger EPS and determine if the deal is accretive or dilutive.
Answer: Combined Net Income = $100M + $30M = $130M.
Combined Share Count = 20M + 5M = 25M shares.
Post-Merger EPS = Combined Net Income / Combined Shares = $130M / 25M = $5.20.
Since $5.20 is greater than the standalone EPS of $5.00, the deal is Accretive by $0.20 per share (+4%). -
Goodwill Determination on Balance Sheet: Company X purchases Company Y for $500,000,000 in cash. On the acquisition date, Company Y has total assets with a fair market value of $420,000,000 and total liabilities with a fair market value of $120,000,000. Calculate (a) Net Identifiable Assets and (b) Goodwill recognized.
Answer: (a) Net Identifiable Assets = Fair Value of Assets – Fair Value of Liabilities = $420M – $120M = $300M.
(b) Goodwill Recognized = Purchase Price – Net Identifiable Assets = $500M – $300M = $200M. -
Earn-Out Contingent Payout Valuation: Under an acquisition agreement, an earn-out bonus of $10,000,000 is payable in Year 3 if EBITDA exceeds $50M. The buyer estimates an 80% probability that the target will hit this target. Discounting at 10% per annum, calculate the expected present value of the earn-out liability today.
Answer: Expected Cash Flow in Year 3 = Probability × Payout Amount = 0.80 × $10,000,000 = $8,000,000.
Present Value (PV) = Expected Cash Flow / (1 + r)3
PV = $8,000,000 / (1.10)3 = $8,000,000 / 1.331 = $6,010,518. -
Enterprise Value (EV) Multiple Comparison: Target Firm has an EBITDA of $25,000,000. Peer precedent transactions show a average Enterprise Value / EBITDA multiple of 8.0x. If Target Firm has $30,000,000 in total debt and $10,000,000 in cash, calculate (a) Implied Enterprise Value and (b) Implied Equity Value.
Answer: (a) Implied Enterprise Value (EV) = EBITDA × EV/EBITDA Multiple = $25M × 8.0x = $200,000,000.
(b) Implied Equity Value = Enterprise Value – Total Debt + Cash = $200M – $30M + $10M = $180,000,000. -
Post-Merger Ownership Split Percentage: Company A (Market Value $800M) merges with Company B (Market Value $200M) in an all-stock transaction where new shares are issued proportional to relative standalone values. Calculate the percentage ownership split of the combined entity for shareholders of Company A and Company B.
Answer: Total Combined Market Value = $800M + $200M = $1,000,000,000.
Company A Shareholder Ownership % = ($800M / $1,000M) × 100 = 80%.
Company B Shareholder Ownership % = ($200M / $1,000M) × 100 = 20%.