
Capital, Credit, and Risk: How Financial Systems Shape Economic Activity
Financial History
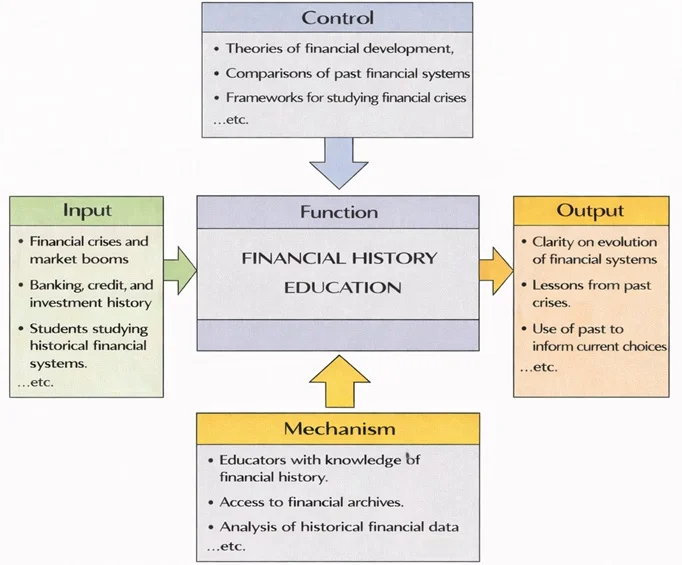
Analyses how financial institutions evolve over time to allocate capital efficiently, manage systematic risk, and underpin long-term macroeconomic growth.
Trade & Commerce History
Shows how international credit mechanisms, clearinghouses, and payment settlement networks enable merchant exchange across diverse global markets.
Industrial & Technological History
Highlights how equity capital markets, debt underwriting, and venture financing drive capital-intensive infrastructure, technological breakthroughs, and large-scale manufacturing.
Comparative Economic History
Compares how distinct institutional banking architectures, regulatory environments, and capital allocation frameworks shape developmental trajectories across sovereign states.
Economic Thought & Theory
Interprets theoretical models of money creation, liquidity preference, interest rate mechanics, and central banking policy across historical schools of thought.
Labor History
Connects institutional debt structures and monetary fluctuations to employment volatility, real wage trends, pension funds, and working-class economic security.
Environmental Economic History
Examines how capital instruments, insurance underwriting, and financial markets respond to ecological resource limits, climate risk, and energy transitions.
Gender & Economic History
Reveals historical disparities in property ownership, legal credit access, and financial inclusion across social groups and gender boundaries.
Economic History – Overview
Provides the master macroeconomic framework contextualizing how financial evolution interacts with state organization, trade regimes, and social transformation.
Key Focus Areas in Financial History
The Development of Banking Systems
The history of banking traces the evolution of institutions that facilitate the storage, lending, and transfer of money.
Early Banking
- Ancient Civilizations: Early banking emerged in Mesopotamia, where temples and palaces safeguarded deposits and provided agricultural loans. The Roman Empire introduced credit mechanisms and currency exchange offices.
- Medieval Europe: Italian city-states like Florence and Venice pioneered commercial banking during the Middle Ages. The Medici family established a major international banking house that financed European trade and statecraft.
The Establishment of Central Banks
- The Bank of England (1694): Established to manage sovereign national debt and stabilize the British pound, serving as the foundational model for modern central banking.
- The Federal Reserve System (1913): Created as the central banking institution of the United States to manage liquidity, prevent banking panics, and conduct monetary policy.
Evolution of Currencies
Currencies have evolved from physical commodity exchange to sovereign fiat units and decentralized digital tokens.
Commodity and Paper Money
- Commodity Money: Early commercial trade relied on gold, silver, and standardized metal coins, such as those minted in ancient Lydia.
- Paper Currency: First introduced in China during the Tang and Song Dynasties to eliminate the logistics of transporting heavy coinage, later spreading across Europe during the Renaissance.
Fiat Money and Cryptocurrencies
- Fiat Money: Unbacked currency given legal tender status by government decree. The collapse of the gold standard in the 20th century gave central banks full authority over money supply management.
- Cryptocurrencies: The inception of Bitcoin (2009) introduced decentralized ledger technology (blockchain), offering peer-to-peer digital monetary settlement.
Development of Stock Markets
Stock exchanges emerged as organized trading platforms to raise risk capital for large ventures.
- Amsterdam Stock Exchange (1602): Formed by the Dutch East India Company to trade public shares and bonds, establishing the world’s first modern stock market.
- London Stock Exchange (1801) & NYSE (1792): Formalized equity trading, providing the primary capital pipeline for 19th and 20th-century industrialization.
Interactive Tool: Fractional Reserve Banking & Credit Multiplier Simulator
This simulator models how fractional reserve banking expands money supply through successive lending cycles. Adjust the Reserve Requirement Ratio (r) and Initial Bank Deposit to observe real-time dynamic changes in total credit expansion, bank reserves, and the theoretical money multiplier ($M = 1 / r$).
Theoretical Money Multiplier (M = 1 / r): 10.0×
Max Potential Money Supply (Base × M): $10,000
Total Bank Credit Created (Supply − Base): $9,000
Historical Crises, Globalization, and Modern Policy
Financial history is marked by major panics that prompted systemic governance reforms:
- The Great Depression (1929–1939): Sparked by stock market crash and mass bank runs, resulting in regulatory structures like the SEC and deposit insurance (FDIC).
- The Bretton Woods System (1944–1971): Established fixed currency exchange rates tied to gold and created the International Monetary Fund (IMF) and World Bank to stabilize global trade finance.
- The Global Financial Crisis (2008): Subprime mortgage lending and complex derivative securitization caused global banking panics, leading to the Dodd-Frank Act and central bank quantitative easing.
Why Study Financial History
Understanding System Evolution & Crisis Management
Studying past credit cycles, stock market bubbles, and panics enables economists, investors, and policymakers to recognize recurring market leverage risks and construct resilient institutional safeguards.
Connecting Finance with Governance
Public finance, sovereign debt issuance, and monetary regulation have historically formed the foundation of state capacity, geopolitical alliance building, and internal social policy stability.
Financial History: Conclusion
Financial history demonstrates how banking institutions, stock exchanges, legal currencies, and crisis frameworks have evolved across centuries. By understanding the historical mechanisms of credit expansion, inflation, and market speculation, society is better equipped to manage current financial systems with stability, innovation, and long-term economic realism.
Frequently Asked Questions about Financial History
What is financial history, and how is it different from general economic history?
Financial history focuses on how money, credit, banking, financial markets, and financial institutions have developed over time. General economic history is broader, covering production, trade, labour, industry, and living standards.
Why does financial history matter for understanding today’s global economy?
Many contemporary financial rules and structures were forged in direct response to historical booms and crashes. Studying this provides perspective on systemic risk and regulatory responses.
What primary records do financial historians analyze?
Financial historians combine quantitative datasets (bank balance sheets, interest rates, stock tickers) with qualitative records (central bank charters, government debt logs, and executive correspondence).
How did central banks evolve into lenders of last resort?
Originally established to finance national war debts, central banks gradually assumed responsibility for stabilizing commercial banking systems by providing emergency liquidity during panics.
Interactive Module: Key Concept Toggles
Click each summary toggle below to reveal detailed explanatory breakdowns of core financial history concepts:
The Evolution of Fractional Reserve Banking
Understanding Speculative Bubbles: Tulip Mania to Dot-Com
The Classical Gold Standard vs. Fiat Money Regimes
Comprehensive Practice & Assessment Module
Section 1: Foundational Review Questions
- What is financial history and why is it significant to study?
Answer: Financial history is the study of the evolution of financial systems, institutions, credit instruments, and monetary policy over time. It provides fundamental lessons on risk management, regulatory frameworks, and market stability. - How did merchant banks in medieval Italian city-states contribute to commercial growth?
Answer: Italian banking families introduced double-entry bookkeeping, bills of exchange, and international transfer networks that significantly reduced international trade transaction costs. - What primary purpose motivated the founding of the Bank of England in 1694?
Answer: It was established to raise funding for the English government to rebuild its naval forces and manage sovereign national debt. - What key innovation distinguished paper bank notes from commodity coinage?
Answer: Paper money eliminated the physical weight and transport risks of heavy precious metals, dramatically accelerating transaction velocity and commercial exchange. - How did the Amsterdam Stock Exchange in 1602 revolutionize capital allocation?
Answer: It allowed public investors to purchase and trade fractional corporate ownership shares (VOC) in secondary markets, enabling companies to raise unprecedented long-term capital. - What regulatory framework emerged in the United States following the 1929 stock market collapse?
Answer: Congress created the Securities and Exchange Commission (SEC) to enforce market transparency and enacted the Glass-Steagall Act to separate commercial banking from investment banking. - What primary function did the 1944 Bretton Woods agreement serve in international finance?
Answer: It established a global fixed exchange rate system pegging international currencies to the U.S. dollar, which was directly convertible to gold at $35 per ounce. - What distinguishes fiat money from commodity-backed currencies?
Answer: Fiat money is established by legal government tender decree and is not redeemable for physical gold or silver commodities.
Section 2: Analytical & Scenario-Based Questions
- How do historical financial panics demonstrate the danger of high systemic leverage?
Answer: High leverage amplifies asset write-downs; when asset values drop slightly, highly leveraged firms face immediate insolvency, triggering contagion panics and credit freezes. - In what ways could decentralized digital currencies challenge sovereign central bank monetary authority?
Answer: Cryptocurrencies operate outside national central banking channels, potentially bypassing capital controls, reducing fractional reserve efficiency, and altering sovereign interest rate transmission. - Analyze the trade-offs between strict financial regulation and financial innovation.
Answer: Strict regulation enhances systemic stability and protects consumers but can restrict credit availability and slow economic expansion; deregulation fosters innovation but risks excessive speculation. - How does interdisciplinary research enhance our understanding of financial history?
Answer: Integrating history, political science, and behavioral sociology shows that financial panics are not purely mathematical failures, but reflect human psychology and regulatory institutional shifts. - How can historical lessons from microfinance and cooperative banking improve financial inclusion today?
Answer: Historical mutual savings banks prove that peer monitoring, community-based underwriting, and simplified credit access successfully bring underbanked groups into formal economies. - Compare the macroeconomic impacts of the 1929 Great Depression with the 2008 Global Financial Crisis.
Answer: In 1929, central bank policy contraction worsened bank runs and deflation; in 2008, immediate global central bank liquidity injections prevented total monetary collapse. - How do sovereign debt markets historically reflect international geopolitical power balances?
Answer: Nations with liquid bond markets and trusted credit reputations borrow at lower interest rates, funding military defense and infrastructure far more effectively than rival states.
Section 3: Numerical Problems & Calculation Solutions
- Money Multiplier & Reserve Requirements: A central bank sets the reserve requirement ratio at r = 8% (0.08).
a) Calculate the theoretical money multiplier (M = 1 / r).
b) If an initial central bank injection of $5,000,000 in cash is deposited into commercial banks, calculate the maximum potential expansion of the total money supply.
Answer:a) Theoretical Money Multiplier:
M = 1 / 0.08 = 12.5×
b) Maximum Potential Money Supply Expansion:
Total Supply = Initial Deposit × M
Total Supply = $5,000,000 × 12.5 = $62,500,000. - Bond Yield to Maturity Calculation: An investor purchases a historical 1-year government bond with a face value of $1,000 for a discounted market price of $920. Calculate the bond’s Yield to Maturity (nominal annual return rate).
Answer:Yield = (Face Value − Purchase Price) / Purchase Price
Yield = ($1,000 − $920) / $920 = $80 / $920 = 0.08695 × 100% = 8.70%. - Compound Inflation & Purchasing Power Loss: A nation experiences severe post-war inflation averaging 15% (× 1.15) per year over 3 consecutive years.
a) Calculate the cumulative price index multiplier after 3 years.
b) If a basket of goods cost $100 initially, calculate its cost after 3 years.
Answer:a) Cumulative Price Multiplier:
Multiplier = (1.15)3 = 1.15 × 1.15 × 1.15 = 1.520875 (≈ 1.521)
b) Final Basket Cost:
Cost = $100 × 1.520875 = $152.09. - Bank Leverage Ratio Determination: A historical merchant bank holds $5,000,000 in equity capital and $45,000,000 in customer debt deposits, taking total assets to $50,000,000.
a) Calculate the bank’s Leverage Ratio (Total Assets / Equity Capital).
b) Calculate the percentage decline in Total Asset values that would completely wipe out the bank’s equity capital, inducing insolvency.
Answer:a) Leverage Ratio:
Leverage = $50,000,000 / $5,000,000 = 10:1 (or 10×).
b) Insolvency Trigger Threshold:
Decline = Equity / Total Assets = $5,000,000 / $50,000,000 = 0.10 × 100% = 10%.
A 10% drop in asset values reduces equity to $0. - Compound Interest vs. Simple Interest over Time: An investor places $2,000 into an early industrial fund earning 6% simple annual interest for 5 years, while a second investor places $2,000 into a fund earning 6% annual compound interest for 5 years. Calculate the final value difference between the two investments.
Answer:Simple Interest Fund:
Interest = $2,000 × 0.06 × 5 = $600.
Total Value = $2,000 + $600 = $2,600.00.
Compound Interest Fund:
Total Value = $2,000 × (1.06)5 = $2,000 × 1.3382255 = $2,676.45.
Difference:
$2,676.45 − $2,600.00 = $76.45 additional gain from compounding. - Real Rate of Return Calculation (Fisher Equation): In a historical economic expansion, a railway bond offered a nominal interest rate of i = 9%. During the same year, general price level inflation was π = 4%. Calculate the exact Real Rate of Return (r) using the formula: (1 + i) = (1 + r) × (1 + π).
Answer:(1 + r) = (1 + i) / (1 + π)
1 + r = 1.09 / 1.04 = 1.048077
r = 1.048077 − 1 = 0.048077 × 100% = 4.81% exact real return. - Foreign Exchange Arbitrage Calculation: In 1890, 1 British Pound (£) exchanges for 5.00 U.S. Dollars ($) in London. In New York, 1 British Pound (£) exchanges for 5.15 U.S. Dollars ($). A merchant transfers $50,000 to London, converts it to Pounds, and immediately exchanges those Pounds back to Dollars in New York. Calculate the gross arbitrage profit (ignoring transaction fees).
Answer:Step 1: Convert $50,000 in London → $50,000 / 5.00 = £10,000.
Step 2: Convert £10,000 back in New York → £10,000 × 5.15 = $51,500.
Arbitrage Profit = $51,500 − $50,000 = $1,500.