
FinTech and Digital Finance focuses on how technology is changing the way people save, borrow, pay, invest, and manage money. It includes digital payments, online banking, mobile finance apps, financial platforms, and new financial service models.
For students, this field is exciting because it combines finance with technology and innovation. It also helps explain the systems many people already use every day, such as mobile transfers, digital wallets, and app-based investing.
If you are interested in the future of finance, this is one of the most relevant subpages in the Finance hub.
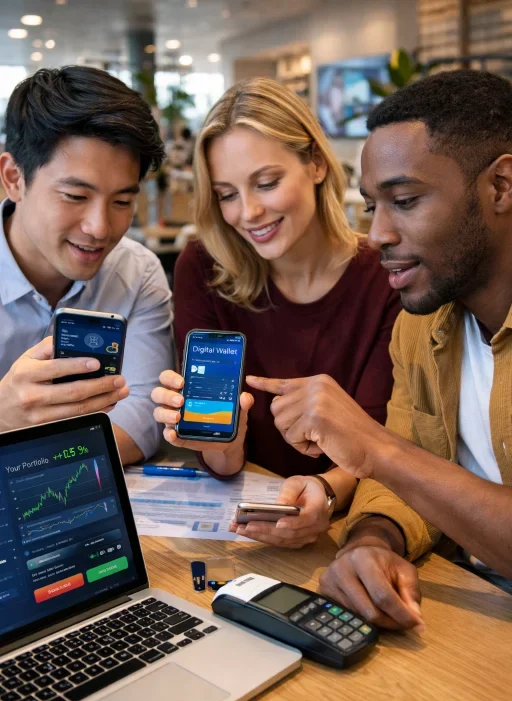
This image shows young professionals exploring mobile finance apps, digital payments, and online investment tools in a collaborative setting. It reflects how financial technology has become part of everyday decision-making, from managing portfolios to making payments. FinTech connects financial services with digital platforms, making access faster, more convenient, and more personalized. The scene illustrates how technology is reshaping how people interact with money in real time.
Digital Infrastructure Reshaping Financial Interaction and Services
What This Field Includes
Digital Payments
Cashless transactions, QR payments, and online transfers have changed how people and businesses move money.
Online Banking and Financial Platforms
Banking services are increasingly delivered through apps and web systems rather than physical branches.
Automation and Financial Workflows
Technology helps financial institutions process transactions faster and reduce manual work.
Platform-Based Investing and Lending
Users can now access investment tools and lending services through digital platforms, often with lower barriers to entry.
Security and Trust in Digital Systems
As finance becomes more digital, cybersecurity, fraud prevention, and identity verification become even more important.
Core Algorithmic Foundation: Digital Payment Take-Rate & Platform Economics
FinTech transaction platforms generate revenue primarily through payment processing fees (take rates) levied on merchant processing volume. The net transaction revenue earned by a payment gateway is governed by the net margin equation:
Where: V = Total Gross Gross Transaction Volume (GTV), t = Merchant MDR percentage take-rate, c = Interchange & network processing cost percentage.
How Students See FinTech in Everyday Life
Example 1: Mobile Wallet Payments
A student pays for food or transport using a mobile app, showing how financial transactions are becoming faster and more integrated.
Example 2: App-Based Savings and Budgeting
Digital tools help users track spending, set goals, and manage money more clearly.
Example 3: Online Investment Platforms
Technology has made investing more accessible, but students still need financial judgment, not just convenience.
Example 4: Fraud Alerts and Security Checks
Digital Finance also teaches students why authentication, monitoring, and financial security matter.
Interactive Payment Gateway Revenue & Margin Simulator
Digital Payment Economics Calculator
Adjust transaction volume, merchant take-rate, and network interchange costs to simulate net revenue and profit margins for a digital wallet or payment processor.
Why Students Are Drawn to FinTech and Digital Finance
It Feels Current and Practical
Students can connect what they learn directly to tools they already use.
It Combines Finance and Technology
This field suits students who like both business systems and digital innovation.
It Opens New Career Pathways
FinTech supports roles in product, operations, compliance, payments, and platform finance.
How to Prepare Early for FinTech and Digital Finance
Build a basic understanding of finance first, then pay attention to how digital systems change user experience, speed, and access.
When you use a finance app, ask: What problem is this solving? How does it make money? What security risks might exist?
That combination of finance thinking and technology awareness is the best preparation for this field.
Interactive Review Questions & Architectural Deep-Dives
Click on each architectural query below to expand detailed technical and financial explanations.
1. What role do Application Programming Interfaces (APIs) play in Open Banking ecosystems?
2. How does machine learning improve credit underwriting over traditional FICO credit scoring?
3. What is "payment tokenization," and how does it protect consumer transactions?
End of Page Exercises
Section 1: Core Knowledge Verification
- Explain the difference between a traditional commercial bank and a "Neobank" (Digital-Only Bank).
Answer: Traditional commercial banks rely on physical branch infrastructure, legacy mainframes, and relationship banking. Neobanks operate entirely digitally via mobile applications without physical branches, leveraging cloud infrastructure to offer lower account fees, instant notifications, and streamlined user interfaces. - What is "RegTech" and how does it assist financial institutions in regulatory compliance?
Answer: RegTech (Regulatory Technology) uses automation, big data, and natural language processing to help financial institutions comply with regulatory mandates, execute automated Anti-Money Laundering (AML) checks, conduct real-time transaction monitoring, and streamline reporting to financial authorities. - Define "Buy Now, Pay Later" (BNPL) and contrast its revenue model with traditional credit card interest.
Answer: BNPL is a point-of-sale financing model that allows consumers to divide purchases into interest-free installments. Unlike credit card issuers that make revenue primarily on consumer interest charges, BNPL platforms charge merchants a higher processing fee percentage (typically 3% to 6%) in exchange for increased cart conversion rates.
Section 2: Strategic FinTech & Industry Scenarios
- Analyze how zero-commission trading platforms (e.g., Robinhood) generate revenue through "Payment for Order Flow" (PFOF). What regulatory controversies surround this practice?
Answer: Instead of charging retail user commissions, retail brokers route user buy/sell orders to wholesale market makers (like Citadel Securities). Market makers pay the broker a fraction of a cent per share (PFOF) for access to retail order volume, making money on the bid-ask spread. Controversies arise because regulators question whether brokers prioritize routing orders to market makers paying the highest fees rather than executing trades at the best market price for retail consumers. - Compare Central Bank Digital Currencies (CBDCs) with decentralized cryptocurrencies like Bitcoin in terms of governance, volatility, and monetary policy control.
Answer: CBDCs are digital legal tender issued, controlled, and backed directly by a central bank, designed to maintain price stability and serve as an efficient payment rail. Cryptocurrencies like Bitcoin are decentralized, permissionless networks governed by consensus algorithms with capped supply schedules; they operate outside central bank monetary control and exhibit significant price volatility. - How do Robo-Advisors automate portfolio management, and what are their primary limitations during extreme market black swan events?
Answer: Robo-advisors use customer risk tolerance questionnaires and algorithms based on Modern Portfolio Theory to automatically allocate capital into low-cost index ETFs and rebalance portfolios. However, during black swan events, algorithms rely on historical variance data that may fail under unprecedented liquidity freezes, lacking human qualitative reasoning and behavioral coaching to prevent panic liquidations.
Section 3: Applied Financial Analytics & Problem Solving
- A digital wallet platform processed $500 Million in total transaction volume last quarter. The merchant discount rate (MDR) average was 2.2% (0.022). Interchange fees paid to issuing banks averaged 1.3% (0.013), and network processing fees paid to Visa/Mastercard averaged 0.2% (0.002). Calculate:
a) Total Gross Revenue generated by the platform.
b) Total Processing Costs paid out by the platform.
c) Net Platform Revenue and Net Take-Rate Percentage.
Answer:
a) Gross Revenue = $500M × 0.022 = $11 Million.
b) Total Costs = $500M × (0.013 + 0.002) = $500M × 0.015 = $7.5 Million.
c) Net Revenue = $11M - $7.5M = $3.5 Million. Net Take-Rate = 2.2% - 1.5% = 0.70% (0.007). - A peer-to-peer (P2P) digital lending platform funds a $20,000 loan for a borrower at an 8% annual fixed interest rate over a 1-year term. The platform charges the borrower an upfront 3% origination fee, and charges the investor a 1% annual servicing fee on principal collected. Calculate:
a) Upfront origination fee collected by the platform.
b) Total interest paid by the borrower at year-end (simple interest).
c) Total Net Income earned by the FinTech platform from this loan transaction.
Answer:
a) Origination Fee = $20,000 × 0.03 = $600.
b) Borrower Interest = $20,000 × 0.08 = $1,600.
c) Platform Servicing Fee = $20,000 × 0.01 = $200. Total Platform Net Income = $600 (Origination) + $200 (Servicing) = $800. - A traditional bank branch processes loan applications at a human operational cost of $450 per application with a processing turnaround time of 5 days. A Neobank implements an automated AI underwriting API that reduces processing cost per application by 85% and reduces processing time by 99%. Calculate:
a) The new operational cost per loan application at the Neobank.
b) The annual operational savings for processing 12,000 loan applications through the automated system.
Answer:
a) Neobank Cost per Application = $450 × (1 - 0.85) = $450 × 0.15 = $67.50.
b) Savings per Application = $450 - $67.50 = $382.50. Annual Operational Savings = 12,000 × $382.50 = $4,590,000 ($4.59 Million).
Frequently Asked Questions
How do neobanks keep customer funds safe without physical branches?
Neobanks typically partner with established, chartered commercial banks (Sponsor Banks) that hold customer deposits. Through these partner banks, customer deposits remain eligible for official government deposit insurance (such as FDIC insurance up to regulatory limits).
What is the difference between open banking and traditional banking?
Traditional banking keeps customer data siloed inside individual financial institutions. Open banking requires financial institutions to allow customers to securely share their financial transaction data with regulated third-party financial applications via APIs.
Why do digital wallets charge different fees for merchant payments vs instant bank transfers?
Merchant payments are charged a Merchant Discount Rate (MDR) paid by the seller to cover credit card interchange fees. Instant bank transfers incur real-time debit network push-payment fees charged directly to the user for bypassing standard multi-day ACH clearing settlement schedules.