
Financial Markets and Institutions is the field that studies how money is transferred, borrowed, invested, and managed through systems such as banks, stock exchanges, bond markets, and central banks.
For students, this area is important because it explains how finance works at the system level. It helps answer practical questions such as: Why do interest rates matter? What do banks actually do? Why do markets rise and fall? How does the central bank influence the economy?
If you want to understand the financial system behind business, investment, and public policy, this is a strong foundation page.
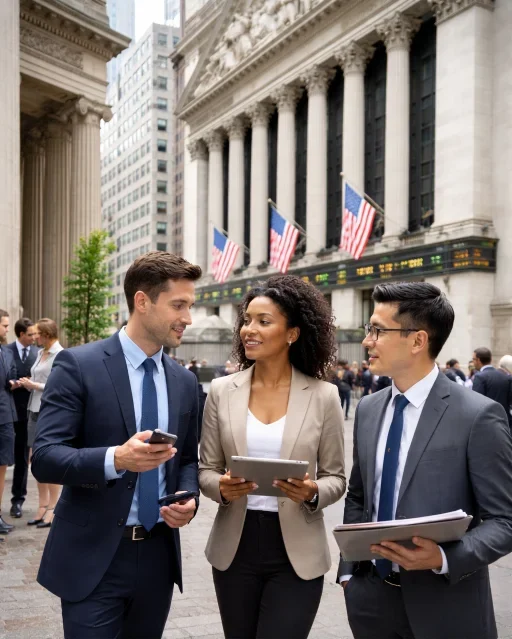
This image represents how financial markets and institutions operate within large, interconnected systems. Stock exchanges, banks, and financial professionals work together to move capital, manage risk, and support economic activity. The scene highlights how financial decisions are influenced by market information, technology, and institutional structures. It reflects the real-world environment where financial systems shape investment, lending, and economic policy.
Market Infrastructure and Intermediation Across Capital Ecosystems
What This Field Covers
Financial Markets
These include stock markets, bond markets, money markets, and foreign exchange markets where financial assets are traded.
Financial Institutions
Banks, insurance companies, investment firms, and other intermediaries help move money between savers and borrowers.
Central Banks and Regulation
Central banks manage interest rates and monetary conditions, while regulators help maintain stability and trust in the financial system.
Intermediation
A key concept in this field is how institutions connect people who have surplus money with those who need funding.
System Stability
This field also looks at financial crises, liquidity problems, and why confidence matters in markets and banking.
Core Intermediation Mechanics & Money Creation Equation
Financial institutions transform short-term liquid deposits from surplus units into long-term loans for deficit units. The deposit expansion capacity of commercial banks within a fractional reserve system is governed by the money multiplier formula:
Where: D0 = Initial primary cash deposit, rr = Required reserve ratio set by the central bank (expressed as a decimal).
Examples Students Can Relate To
Example 1: A Business Loan
A small business borrows from a bank to expand. This simple action reflects financial intermediation in practice.
Example 2: A Company Issues Shares
When a company raises money from investors in the stock market, financial markets help fund growth.
Example 3: Interest Rates Rise
Higher rates may affect mortgages, business borrowing, and investment decisions across the economy.
Example 4: Market Volatility
Students can see how news, policy changes, or global events influence market confidence and pricing.
Interactive Money Multiplier & Banking Reserve Simulator
Bank Credit Creation Calculator
Adjust the initial cash deposit and the central bank’s reserve requirement to see how commercial banking intermediation expands money creation in the financial system.
Why Students Benefit from This Topic
It Explains the Bigger Picture
This subfield helps students connect personal finance, business finance, and government policy.
It Makes News More Understandable
Terms like “rate hike,” “liquidity,” or “bank stress” become clearer when students know the system structure.
It Supports Many Finance Careers
Banking, investment, regulation, and policy work all rely on this foundation.
How to Prepare Early for Financial Markets and Institutions
Start by learning the roles of banks, markets, and central banks. Basic economics helps a lot, especially supply and demand, inflation, and interest rates.
When you read financial news, ask: Which market or institution is involved here? Who is lending, borrowing, investing, or regulating?
That systems view is the best way to prepare for this field.
Interactive Concept Breakdown & Self-Assessment Toggles
Click on each foundational question below to expand the detailed explanation and system-level breakdown.
1. What is the fundamental operational difference between primary and secondary capital markets?
2. How do commercial banks perform “maturity transformation,” and why does it create systemic liquidity risks?
3. How does a central bank’s open market operation (selling bonds) impact market interest rates and money supply?
End of Page Exercises
Section 1: Essential Knowledge & Core Concept Review
- Define the term “financial intermediation” and identify two major categories of financial intermediaries operating in global capital markets.
Answer: Financial intermediation is the process by which institutional entities gather funds from surplus units (savers/investors) and allocate those funds to deficit units (borrowers/firms). Two major categories are Depository Intermediaries (e.g., commercial banks, savings institutions) and Non-Depository Intermediaries (e.g., pension funds, insurance companies, mutual funds). - Distinguish between money markets and capital markets in terms of security maturity structures and financial purposes.
Answer: Money markets deal strictly in short-term debt instruments with original maturities of one year or less (e.g., Treasury bills, commercial paper) to facilitate liquidity management. Capital markets trade long-term debt and equity securities with maturities exceeding one year (e.g., 10-year treasury notes, corporate bonds, common stocks) to fund permanent, long-term capital investments. - What role do central banks play as the “lender of last resort” during financial crisis periods?
Answer: As lenders of last resort, central banks provide emergency liquidity loans to solvent but temporarily illiquid financial institutions that face sudden withdrawal panics, preventing localized liquidity shortages from cascading into broader systemic financial collapses.
Section 2: Critical Thinking & Policy Analysis Scenarios
- Evaluate the trade-off commercial banks face between maintaining high liquidity versus maximizing profitability. How does regulatory policy influence this balance?
Answer: Liquid assets (like cash reserves or overnight central bank deposits) are highly safe and easily accessible during panics, but yield low or zero interest, depressing bank return on equity (profitability). Illiquid assets (like 15-year corporate loans) yield higher interest margins but cannot be converted to cash instantly. Central bank reserve requirements and liquidity coverage ratios (LCR) legally force banks to maintain minimum liquid buffers, preventing over-leveraging at the expense of systemic safety. - If an economy experiences sudden demand-pull inflation, how would a central bank use its monetary policy toolkit to stabilize prices, and what ripple effects occur in stock and bond markets?
Answer: The central bank would tighten monetary policy by raising policy interest rates, increasing required reserve ratios, or selling government securities via open market operations. This reduces money supply and elevates borrowing costs. In bond markets, rising interest rates cause bond prices to fall (inverse relationship). In stock markets, higher interest rates raise discount rates applied to equity valuation models and reduce corporate borrowing/consumer spending, often leading to lower stock valuations. - Analyze why asymmetric information (specifically moral hazard and adverse selection) justifies strict regulatory oversight of financial institutions.
Answer: Asymmetric information occurs when one party in a financial transaction possesses superior information. Before a transaction, adverse selection leads risky borrowers to actively seek loans more aggressively than safe borrowers. After a transaction, moral hazard incentivizes borrowers or bank executives to take excessive risks if losses are insured by government bailouts or deposit safety nets. Regulatory mandates (capital requirements, audit disclosures, stress testing) reduce information gaps and prevent high-risk behavior that endangers retail depositors.
Section 3: Applied Financial Mechanics & Quantitative Calculations
- An investor deposits $50,000 in cash into a commercial bank. The central bank mandates a strict required reserve ratio of 8% (0.08). Assuming no excess reserves are held and zero currency leakage occurs in the economy, calculate:
a) The required reserves the bank must keep from this deposit.
b) The initial loan amount the bank can extend to borrowers.
c) The theoretical maximum expansion of total money supply generated across the entire banking system.
Answer:
a) Required Reserves = $50,000 × 0.08 = $4,000.
b) Initial Loan Capacity = $50,000 – $4,000 = $46,000.
c) Maximum Money Supply (M) = $50,000 × (1 / 0.08) = $50,000 × 12.5 = $625,000. - A commercial bank currently holds $800 Million in total demand deposits, $120 Million in total cash reserves at the central bank, and $680 Million in long-term loans. The central bank required reserve ratio is 10% (0.10). Calculate:
a) The dollar value of required reserves the bank must legally hold.
b) The bank’s current excess reserves available for additional lending.
Answer:
a) Required Reserves = $800M × 0.10 = $80 Million.
b) Excess Reserves = Total Reserves ($120M) – Required Reserves ($80M) = $40 Million. The bank can immediately extend up to $40 Million in new loans. - A 1-year Treasury Bill with a face value (par value) of $10,000 is currently selling in the secondary money market for $9,523.81. Calculate:
a) The annual discount yield percentage earned by a investor holding the T-bill to maturity.
b) If market interest rates rise next week and newly issued T-bills offer a 6% yield, calculate the new market price of this $10,000 face value T-bill.
Answer:
a) Yield = [($10,000 – $9,523.81) / $9,523.81] × 100 = ($476.19 / $9,523.81) × 100 = 5.00%.
b) New Price = $10,000 / (1 + 0.06) = $10,000 / 1.06 = $9,433.96. (Demonstrates that rising market interest rates reduce secondary market bond prices).
Frequently Asked Questions
Why do interest rates set by central banks affect consumer mortgages and corporate loans?
Central bank policy rates establish the benchmark cost at which commercial banks borrow money overnight. When central banks adjust policy rates, commercial banks pass those cost changes onto retail and corporate customers through adjusted mortgage, auto loan, and line-of-credit interest rates.
What is the difference between direct finance and indirect finance?
Direct finance occurs when borrowers borrow funds directly from financial market lenders by issuing financial claims/securities (like selling stocks or bonds). Indirect finance involves a financial intermediary (like a bank) standing between the borrower and lender to collect deposits and issue loans.
How do money markets differ from equity markets?
Money markets trade ultra-short-term, highly liquid debt instruments (under 1 year) designed for temporary cash reserves. Equity markets trade fractional ownership shares in public corporations with perpetual life, offering variable dividends and capital appreciation potential.